Advisers reviewing a dismissal case file

15–75 Days’ Notice Checklist: Portugal Dismissal Procedures

In Portugal, employers may only terminate contracts for the specific grounds set out in the Labour Code: disciplinary dismissal, extinction of the job position, collective dismissal, unsuitability, expiry, or mutual agreement. Procedure decides legality as much as the underlying facts. Workers should keep every written notice they receive. Employers should document each step in real time or bring in specialist counsel before acting.


TL;DR:

  • Employers must strictly follow the specific dismissal category required by law, such as expiry, mutual agreement, or misconduct, to avoid unlawful termination claims.
  • Disciplinary dismissals require a detailed nota de culpa, a timely employee response, and a reasoned final decision based solely on the alleged facts; procedural errors risk a court ruling for reinstatement or higher damages.
  • Redundancy and collective dismissals necessitate formal communications with concrete grounds, proper negotiation with worker representatives, detailed documentation, and filing with authorities before termination can proceed legally.
  • Notice periods are strictly scaled according to seniority, with 15 days for less than one year and up to 75 days for over ten years; labor credits and final payments must be settled immediately at termination.
  • Workers can contest dismissals by filing a court challenge within weeks, provided they collect all relevant documentation and act promptly; dismissing protected workers without additional procedural steps is a high legal risk.

Outsourcing-portugal
Keep Portugal Terminations Compliant
Outsourcing-Portugal supports international companies with Portuguese employment, payroll, legal compliance, and HR requirements.

Explore employment outsourcing

Table of Contents

What Are the Types of Dismissal Procedures in Portugal?

Portugal’s Labour Code closes the door on informal firing. There is no “at will” employment here, and any despedimento (dismissal) outside the recognized categories is automatically unlawful, regardless of how justified the employer feels. Dismissal without just cause or for political or ideological reasons is expressly prohibited, which sets the tone for everything that follows.

Six modalities cover the field:

  • Caducidade (expiry): the contract ends on its own when a fixed term concludes or a specific condition is met. No dismissal decision is required, but formal notice is still expected.
  • Revogação (mutual agreement): employer and employee sign off on ending the relationship voluntarily, often with a negotiated payment. If the signature is not notarized, the worker has seven days to revoke the agreement, which surprises a lot of employers who assume the deal is final on signing.
  • Despedimento por justa causa (disciplinary dismissal): triggered by serious employee misconduct. No severance is owed if the dismissal is upheld, but the procedural bar is high.
  • Extinção do posto de trabalho (extinction of the job position): the role itself disappears due to restructuring or market conditions, not the employee’s conduct. Severance and notice apply.
  • Inadaptação (unsuitability): the employee cannot adapt to reasonable changes in the job, typically after new technology or reorganized duties. Severance and notice apply here too.
  • Despedimento coletivo (collective dismissal): multiple positions are eliminated at once, following the same logic as extinction of post but with added negotiation obligations.

The government’s own guidance on cessation of employment contracts walks through each category and directs employers to the Autoridade para as Condições do Trabalho (ACT) for procedural questions. Getting the category wrong at the outset is one of the most common ways employers end up defending an “illicit dismissal” claim later, even when the underlying business reason was entirely legitimate.

How Does the Disciplinary Dismissal Procedure Work?

Justa causa dismissals follow the strictest script in Portuguese labor law, and courts read that script literally. CMS Law’s expert guide to Portuguese dismissals confirms that skipping or rushing any stage can turn a legitimate firing into an expensive court loss.

Here is the sequence employers must follow:

  1. Preliminary inquiry (optional but common). Some employers run an internal fact-finding review before issuing formal charges, especially when the misconduct is unclear or disputed.
  2. Communication of intention to dismiss plus nota de culpa. The employer sends a written statement of guilt describing the alleged facts in enough detail for the employee to mount a defense. Vague language here is the single biggest procedural weakness employers create for themselves.
  3. Suspension (if applicable). The employer may suspend the employee with pay while the process runs, though this is not mandatory in every case.
  4. Right to consult the file. The employee can review all evidence gathered against them before responding.
  5. Written response window. The employee has 10 business days to submit a defense, request witnesses, and challenge the facts.
  6. Evidence gathering and witness statements. The employer must actually consider what the employee submits, not just go through the motions.
  7. Final decision with written reasoning. The employer issues a reasoned written decision, which must rely only on the facts already stated in the nota de culpa.

Missing a deadline, or basing the final decision on facts never mentioned in the nota de culpa, is a defect courts treat seriously. A vague nota de culpa or a denied opportunity to present witnesses is enough to convert a disciplinary dismissal into an illicit one, exposing the employer to reinstatement or a significantly higher indemnity.

Courts also apply a proportionality test. Even clear misconduct must make continued employment objectively impossible, weighed against the employee’s record and the severity of the act. A single late arrival will not clear that bar. Repeated insubordination after prior warnings usually will.

Pro Tip: Keep a dated paper trail from day one, not just once you decide to dismiss. Courts scrutinize whether the employer’s story stayed consistent from the first internal memo to the final decision letter, and any drift between those documents undermines the whole case.

What Steps Apply to Redundancy and Collective Dismissals?

Extinction of post applies when a single role disappears. Collective dismissal kicks in once a set threshold of positions is eliminated within a short window, and it carries a heavier procedural load because worker representatives get a formal seat at the table.

The employer’s opening communication has to include specific content, not a general announcement:

  • The grounds for the dismissal, described concretely rather than in boilerplate language.
  • A full personnel table showing roles, categories, and how the change affects staffing.
  • The objective selection criteria used to choose which employees are affected.
  • The exact number and category of positions being eliminated.
  • The method used to calculate compensation for each affected worker.

Once that communication goes out, an information and negotiation phase opens with worker representatives or, where none exist, directly with affected employees. DGERT’s own guidance on collective dismissals requires minutes of these negotiation meetings, and both the initial communication and the final outcome must be filed with DGERT (Direção-Geral do Emprego e das Relações de Trabalho) before the process closes. Skipping the negotiation phase, or notifying DGERT after the fact instead of during the process, renders the dismissal unlawful outright.

Selection criteria deserve extra caution. When several employees hold similar roles, courts treat ad hoc or inconsistent selection as strong evidence of a disguised dismissal, even when the business reason for cutting the role is entirely genuine. Employers restructuring several similar positions should document why each specific person, and not a colleague in the same role, was selected.

How Much Notice and Severance Does a Worker Get?

Notice periods in Portugal scale with seniority, and getting this wrong is a common, avoidable mistake. According to MLGTS’s employment practice guide, the statutory notice grid runs as follows:

  • Under 1 year of service: 15 days’ notice
  • 1 to 5 years of service: 30 days’ notice
  • 5 to 10 years of service: 60 days’ notice
  • 10 or more years of service: 75 days’ notice

Severance for extinction of post, unsuitability, and collective dismissal is generally based on base pay and length of service, applying to contracts signed from October 1, 2013 onward. Contracts predating that reform follow transitory rules that can produce a higher figure, so checking hire date against the applicable regime matters before quoting a number to either side.

Fixed-term and probationary contracts follow their own shorter rules, and it is worth confirming these separately rather than assuming the standard grid applies. ACT’s online compensation simulators let both workers and employers estimate the exact payout before any letter goes out, which avoids a lot of avoidable disputes over arithmetic.

Beyond notice and severance, a departing employee is owed a set of labor credits regardless of which modality applies:

  • Any outstanding salary through the last day worked.
  • Proportional holiday pay and holiday allowance for the current year.
  • Christmas allowance (subsídio de Natal) accrued proportionally.
  • Any overtime or expense reimbursements still pending.

These credits are due at termination, not on the next regular payroll cycle, and employers who delay payment invite an additional claim on top of the original dismissal dispute.

How Can a Worker Contest a Dismissal in Portugal?

Workers who believe their dismissal was unlawful have a narrow but workable path, and timing determines whether that path stays open.

  1. File an impugnação (judicial challenge) with the competent labor court. Deadlines are strict, so acting within weeks of receiving the final decision is far safer than waiting months.
  2. Preserve every document before filing: the nota de culpa, the final decision letter, any correspondence about compensation, and contact details for potential witnesses.
  3. Avoid treating any payment as final. If an employer pays compensation and the worker accepts it without promptly rejecting or contesting the amount, courts may treat that as acceptance of the dismissal. Workers who intend to fight should say so in writing when the payment arrives.
  4. Contact ACT or a union representative early. Both can advise on whether the procedural steps were followed correctly and flag obvious defects.
  5. Pursue the judicial hearing, where a court decides whether the dismissal was lawful and, if not, whether the remedy is reinstatement or indemnity.

If a court finds the dismissal illicit, the worker generally chooses between reinstatement in the same role and an increased indemnity in lieu of reinstatement. Back pay for the period between dismissal and the court’s decision is often part of the award, which is exactly why employers who drag out a weak case tend to pay far more than if they had negotiated early.

Which Protections and Procedural Traps Should You Watch For?

Certain workers carry extra legal shielding, and dismissing them without extra steps is one of the fastest ways to lose a case regardless of the underlying facts.

  • Pregnant employees, recent mothers, and workers on parental leave cannot be dismissed without a prior opinion from CITE (Commission for Equality in Labour and Employment). Proceeding without that opinion is a defect on its own, separate from whatever grounds the employer cites.
  • Union representatives and works council members enjoy similar reinforced protection, requiring extra procedural steps before any termination can proceed.
  • Vague or generic nota de culpa language remains the most frequent disciplinary dismissal defect, as CMS Law’s guide to Portuguese dismissals notes.
  • Missing or inconsistent selection criteria in extinction of post or collective dismissal cases signals a disguised dismissal to reviewing courts.
  • Late payment of labor credits or severance creates a second, independent complaint on top of any dispute about the dismissal itself.

Pro Tip: If you are an employer handling a reorganization that touches a protected worker, get a CITE opinion before drafting the termination letter, not after. Retrofitting the paperwork once the process has started rarely satisfies a reviewing court.

Documentation Checklist and Timeline for Dismissal Procedures

Both sides benefit from a simple record-keeping habit built around the actual statutory clock.

Employers should keep: dated internal reports on the underlying facts, copies of every written notice sent to the employee, minutes from any negotiation or consultation meetings, DGERT submission receipts where applicable, the full compensation calculation with supporting figures, and a copy of the Social Security cessation report referencing Mod. RV1009-DGSS.

Workers should keep: every written communication received, bank receipts showing what was actually paid, a personal copy of the nota de culpa, contact details for any witnesses who saw relevant events, and the final work certificate (certificado de trabalho) confirming dates of employment.

Stage Typical timing
Nota de culpa issued Start of disciplinary process
Employee’s written response 10 business days from notice
Final decision issued After evidence review, with written reasoning
Notice period before termination 15 to 75 days, based on seniority
Social Security cessation report By the 10th of the following month
Judicial challenge (impugnação) Within weeks of the final decision

When Should You Bring in Outside Counsel or an EOR Partner?

Some situations are not worth handling alone. A reorganization touching several similar roles, a protected worker who needs a CITE opinion, cross-border staff whose contracts sit under more than one legal framework, or any dismissal where litigation already looks likely all justify bringing in specialist help before, not after, the first letter goes out.

What a specialist actually does is procedural: auditing the planned steps against the Código do Trabalho, drafting the nota de culpa or collective communication so it survives scrutiny, liaising with DGERT on filings, and running the final payroll settlement so labor credits land correctly and on time. That combination of legal precision and payroll execution is where most in-house teams, especially those managing Portuguese staff from abroad, run into trouble.

— Paulo

How Outsourcing-Portugal Keeps Terminations Compliant

Outsourcing-Portugal exists for exactly the moment this article describes: an international employer who needs a Portuguese termination handled correctly, without hiring local employment lawyers from scratch or guessing at DGERT filing rules. As your Employer of Record, we run compliance audits before a termination letter goes out, prepare documentation templates that match what courts actually expect, handle DGERT liaison on collective and extinction-of-post cases, and settle final payroll so labor credits are paid correctly and on schedule.
Outsourcing-portugal

That combination cuts the two biggest risk points employers face: a procedural defect that turns a lawful dismissal into an expensive court loss, and a payroll delay that opens a second complaint on top of the first. If you are planning a reorganization, a single dismissal, or you simply want a second set of eyes before you send a nota de culpa, request a procedural audit through our Employer of Record and payroll services page and get a clear read on your exposure before you act.

Where to Verify Dismissal Rules and Download Official Forms

For the government’s own summary of termination modalities and Social Security reporting forms, start with gov.pt’s cessation of employment guidance. ACT’s compensation simulators confirm severance math. DGERT’s collective dismissal FAQ covers filing steps, and the STJ’s thematic case law notes show how courts actually rule on disputed cases. For CITE opinions on protected workers, contact CITE directly before proceeding.
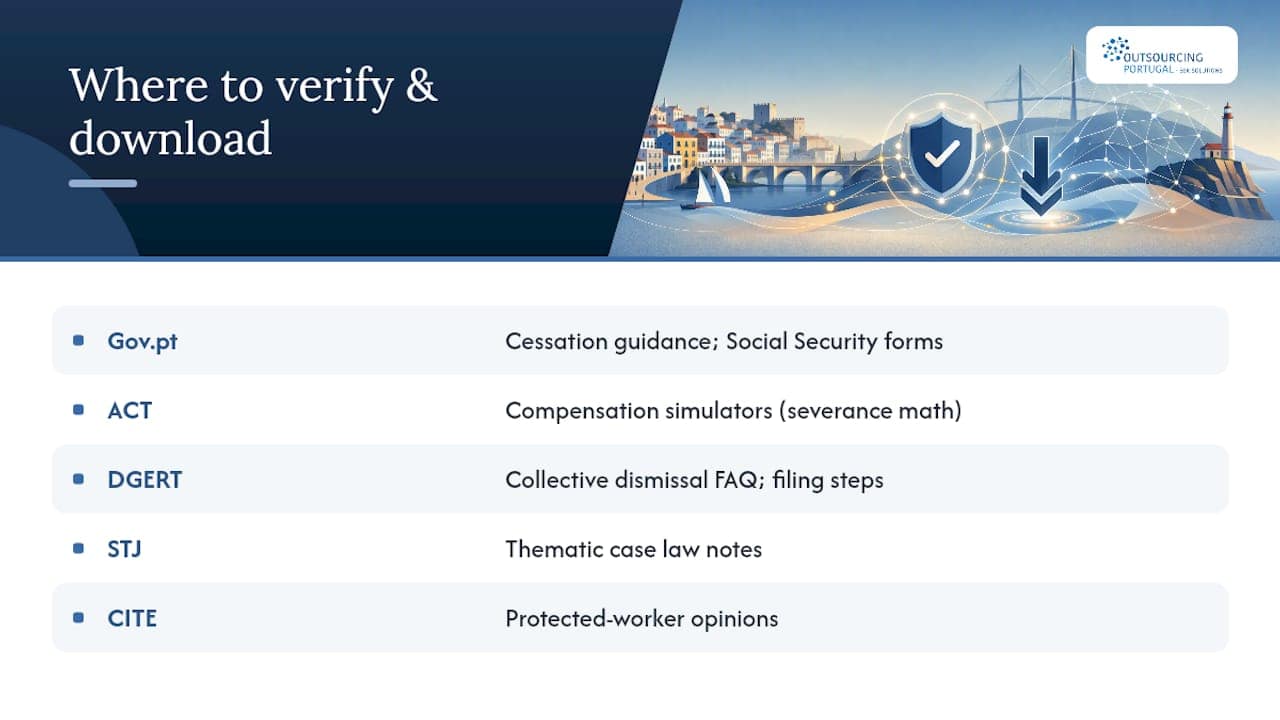
Where to Verify Dismissal Rules and Download Official Forms — overview diagram

This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.

Sources

FAQ

What Are the Requirements to Dismiss a Permanent Employee in Portugal?

Employers need a lawful ground from the closed list in the Código do Trabalho, such as justa causa or extinction of post, plus strict adherence to the matching procedure, including written notice and, for disciplinary cases, a properly drafted nota de culpa.

What Rights Do I Have if I Am Dismissed in Portugal?

You are entitled to written reasoning for the decision, any applicable notice period or severance, all outstanding labor credits, and the right to challenge the dismissal in court if you believe the grounds or procedure were defective.

What Is the Notice Period for Dismissal in Portugal?

Statutory notice runs from 15 days for under one year of service up to 75 days for 10 or more years of service, based on the seniority grid set out in Portuguese employment practice guides.

How Many Days’ Notice Must I Give My Employer if I Resign?

Resignation notice periods differ from employer-initiated dismissal notice and typically follow separate rules set in the employee’s contract or collective agreement, so check your specific contract terms rather than assuming the dismissal grid applies.

Can My Employer Change the Reason for My Dismissal After the Fact?

No. Courts do not allow employers to introduce new grounds once the nota de culpa or dismissal communication has been issued, which is why contemporaneous documentation matters so much for employers defending a claim.
Calculating Portugal employee employment costs

Plan for 1.7x: Portugal Employer Costs and When to Use an EOR

Budget roughly between one and two times a base gross salary once mandatory Portuguese employer costs are added in. The main drivers are the Segurança Social employer contribution, the 13th and 14th-month subsidies, the FCT and FGCT compensation funds, work-accident insurance, and a meal allowance. Most companies underestimate this multiplier because they price only the headline social security rate. Run those numbers through a calculator or an Employer of Record before you quote a candidate a start date.


TL;DR:

  • Employers should budget around 1.7 times the gross salary to cover all costs, including Segurança Social, subsidies, insurance, and funds, not just the headline social security rate.
  • FCT and FGCT funds add roughly 1.075 percent of salary for eligible contracts, which many companies overlook in their initial budgets.
  • Visa and immigration costs for non-EU employees typically require budgeting around €1,900 minimum salary thresholds and several hundred euros in government fees, with timelines taking weeks or months.
  • Using an Employer of Record can streamline compliance, contract setup, and payroll registration, especially for first hires, by consolidating legal, tax, and insurance requirements under one provider.

Outsourcing-portugal
Plan Your Portugal Hiring Costs
Outsourcing-portugal helps international companies manage hiring, payroll, legal compliance, and HR support without setting up a local entity.

Explore Portugal outsourcing

Table of Contents

What Does Custo De Vida Portugal Empresas Actually Include?

“Custo de vida Portugal empresas” gets searched a lot, but it’s a slightly loose phrase. What international employers actually need is the employer cost of employment (sometimes called the “loaded cost” or “total cost of employment”) in Portugal, not the personal cost of living for an individual worker. That distinction matters because the two numbers move independently. A Lisbon software engineer’s personal cost of living affects the salary you need to offer to be competitive; it has nothing to do with what you, as the employer, owe on top of that salary in taxes, funds, and benefits.

This section breaks down every mandatory line item that sits between the gross salary you agree to and the actual invoice your finance team pays each month.

Segurança Social (employer social security) is the biggest line. The standard employer rate is 23.75% of gross salary, and critically, it applies to the employee’s full gross remuneration, including the 13th and 14th-month subsidies. A common budgeting mistake is modeling this on 12 months of pay instead of 14, which quietly understates your annual provision by roughly a sixth.

FCT and FGCT compensation funds add a smaller but real cost. These two funds, designed to cover severance-related liabilities, combine to roughly 1.075% of remuneration for eligible contracts. It is a separate line from Segurança Social and easy to miss in a first-pass budget.

Work-accident insurance is mandatory from day one of employment. Rates vary by activity, and office-based roles typically sit at the lower end of a 0.5% to 2% band, while higher-risk industries pay more. Confirm your specific band with an insurer before you finalize any hiring budget, because a generic estimate here is one of the more common places companies get caught out.

13th and 14th-month subsidies (subsidio de Natal and subsidio de ferias) are statutory, not discretionary. They function as an extra month of salary each, typically paid around Christmas and before the summer vacation period, and both are subject to the employer Segurança Social rate above.

Meal allowance is near-universal in Portuguese employment practice, even though it is not always technically mandatory by law. Employers typically pay it as a meal card rather than cash, since card-based allowances carry a higher tax-exempt ceiling than cash payments. Anything paid above the exempt threshold becomes taxable income for the employee and adds to your payroll cost base.

Hiring in Portugal is not just a signature on a contract. Compliance runs across employment law, payroll, Social Security, insurance, and sometimes immigration. Treating a signed contract as the finish line is one of the most common compliance mistakes foreign employers make](https://www.lvpadvogados.com/hiring-in-portugal-labour-and-immigration-compliance-is-more-than-a-contract).

  1. Draft a contract with the required legal terms and communicate the new hire to Social Security before or on the employee’s start date.
  2. Confirm work-accident insurance is active before the first day worked, since gaps here carry real liability exposure.
  3. Check applicable Collective Bargaining Agreements (CBAs). CBAs frequently set minimum salaries or working conditions above the statutory floor, and skipping this check is how companies end up underpaying legally without realizing it.
  4. Set up IRS payroll withholding and establish recordkeeping practices that satisfy Portuguese tax authority requirements.

Pro Tip: Before you post a salary range externally, check whether a CBA applies to that role’s sector. It can quietly raise your minimum offer by hundreds of euros a month and change your whole budget.

Getting this sequence wrong rarely shows up immediately. It surfaces months later as a Social Security audit query or a back-pay claim, which costs far more to fix than to prevent. A payroll outsourcing partner can absorb most of this administrative risk directly.

What Visa Costs Apply When Hiring Non-EU Employees?

Non-EU hires add a layer of immigration cost and timeline risk that EU hires don’t carry. The distinction that matters most for budgeting is between a temporary stay authorization, valid up to 12 months, and a full residence permit, which carries longer-term obligations and renewal cycles.

  • Salary thresholds: immigration guidance commonly references minimum declared salaries for certain permit categories, with figures around €1,900 cited for highly skilled roles.
  • Government fees: analysis and issuance fees for residence permits are commonly in the low hundreds of euros, though exact amounts depend on the permit type and category.
  • Timelines: processing can stretch over weeks to months, so immigration steps need to start well ahead of a planned start date, not alongside it.
  • Payroll alignment: the salary figure used for immigration purposes must match what actually appears on payroll. A mismatch between declared remuneration and payroll practice is a documented risk area that can jeopardize a permit renewal.

Immigration and payroll registration need to move in parallel, not sequentially. If your visa paperwork quotes one salary and your payroll system runs another, you’ve created a compliance gap before the employee has even started.

How Much Does a €36,000 Salary Really Cost an Employer?

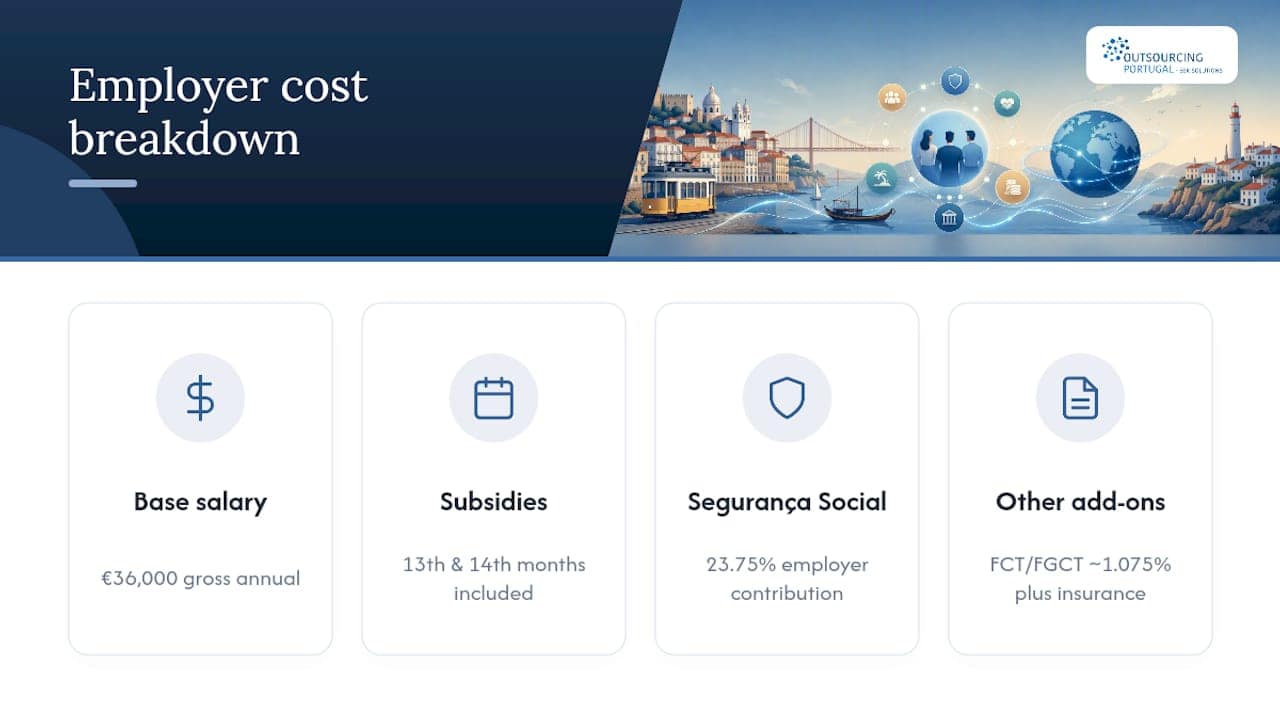
Here’s the math behind the multiplier, using a €36,000 gross annual base salary as the model.

Add the base salary, subsidies, Segurança Social, FCT/FGCT, and insurance together and you land close to €52,500 to €52,800 before accounting for meal allowance, which puts the loaded multiplier right around 1.7 times the base salary. That figure lines up with what payroll providers report as typical when subsidios, funds, insurance, and meal cards are all counted.

Breakdown of Portugal employer salary costs

The most common modeling mistake is stopping at Segurança Social and ignoring FCT/FGCT and insurance entirely, which can understate the true employer cost by several percentage points. The Employment Cost Calculator Portugal 2026 lets you run your own salary and industry inputs against this same structure.

How Should You Budget and When Does an EOR Make Sense?

A workable budget checklist covers five lines: Segurança Social on 14 months, FCT/FGCT, your confirmed work-accident insurance band, meal allowance policy, and any CBA-driven salary floor for the role’s sector.

Watch for vendor quotes that skip detail on any of these. Quotes that omit 13th/14th-month treatment, leave the insurance band unspecified, or gloss over FCT/FGCT are a frequent source of under-budgeting, and they tend to surface as surprise invoices three or four months into the employment relationship, not on day one.

  • Ask any payroll or EOR vendor for a full line-item breakdown, not a single blended percentage.
  • Confirm which CBA, if any, applies to the role before signing off on a salary offer.
  • Get the work-accident insurance band in writing before the hire starts.

Pro Tip: If a vendor’s quote is a single “all-in” number with no breakdown, ask them to itemize it. A quote that can’t be broken into Segurança Social, FCT/FGCT, insurance, and subsidios is a quote you can’t audit.

An Employer of Record earns its cost when speed and compliance risk outweigh the appeal of running payroll in-house, particularly for a first hire in Portugal or a small team where building internal payroll expertise isn’t worth the overhead. Compare that route against building offshore payroll infrastructure directly before committing either way.

What International Employers Consistently Get Wrong

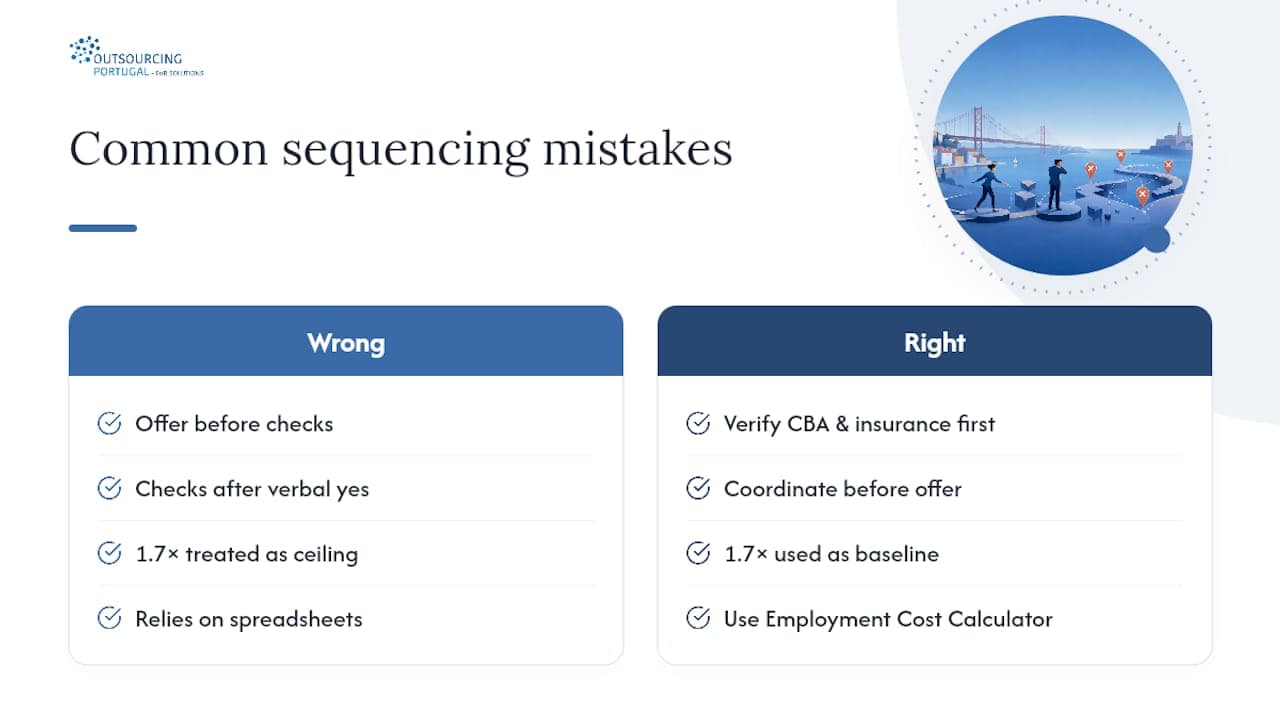
The single biggest mistake we see from clients arriving in Portugal for the first time isn’t a math error. It’s sequencing. Companies quote a candidate a number, get a verbal yes, and only then start checking whether a CBA applies to that role or whether the insurance band they assumed actually matches the job’s risk classification. By the time the gap surfaces, the offer has already been made.

What International Employers Consistently Get Wrong — overview diagram

The other pattern worth naming: companies that treat the 1.7 times multiplier as a ceiling rather than a baseline. It’s a reasonable planning number for a standard office role, but industries with higher work-accident insurance bands, or roles covered by a CBA with richer benefits, push past it. Our own clients use the Employment Cost Calculator specifically because a static multiplier from a blog post can’t account for their sector or their specific hire.

What actually reduces risk isn’t more spreadsheets. It’s moving payroll registration, insurance activation, and CBA verification into a single coordinated process before an offer goes out, which is precisely where outsourced payroll and EOR support earn their fee.

— Paulo

Get an Accurate Employer Cost Estimate Before You Hire

This budgeting exercise can be simplified into a single number without the guesswork of stitching together Segurança Social rates, insurance bands, and CBA checks on your own. A full Employer of Record and payroll partner in Portugal can handle contract drafting, Social Security registration, work-accident insurance, IRS withholding, and visa coordination for non-EU hires under one service.

Outsourcing-portugal

If you’re modeling a specific salary or role right now, run it through the Employment Cost Calculator Portugal 2026 to get a figure tailored to your industry and insurance band, rather than a generic multiplier. From there, request a tailored quote through our Employer of Record Portugal service and we’ll walk you through exactly how the numbers apply to your hire, before you make an offer, not after.

Where These Figures Come From

The Segurança Social rate and its treatment of subsidios come from PwC Portugal’s payroll guide. FCT/FGCT figures, insurance bands, and the loaded multiplier are sourced from WhichPayroll’s Portugal guide. Compliance sequencing comes from LVPA Advogados, and immigration salary thresholds and fees from ICLG’s corporate immigration guide.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.

Sources

FAQ

What Is the Typical Employer Cost Multiplier in Portugal?

Most companies should budget roughly around 1.7 times base gross salary, with 1.7 times cited as a common working figure once Segurança Social, subsidios, FCT/FGCT, insurance, and meal allowance are all included.

Does Segurança Social Apply to the 13th and 14th-Month Subsidies?

Yes. The 23.75% employer rate applies to gross remuneration including both subsidies, which is why modeling on 14 months rather than 12 avoids under-budgeting.

How Much Do FCT and FGCT Add to Employer Costs?

FCT and FGCT combined typically add roughly 1.075% of remuneration for eligible contracts, on top of the Segurança Social contribution.

What Salary Threshold Applies for Non-EU Work Visas?

Immigration guidance commonly references figures around €1,900 for certain highly skilled categories, though the applicable threshold depends on the specific permit route.

Should a Company Use an EOR or Set Up a Local Entity?

An Employer of Record is usually the faster, lower-risk route for a first hire or small team, since it avoids entity setup while keeping payroll, Social Security registration, and compliance handled under one contract with a partner like Outsourcing-portugal.

Administrator completing online employer registration

Use Empresa Online to Secure Employer Registration in Portugal

Any person or company that hires under an employment contract in Portugal must be registered as an employer with Segurança Social. Companies incorporated through Empresa Online usually get this done automatically, with a Social Security Identification Number issued in the same process. Sole traders hiring their first worker don’t get that shortcut. You need to file form RV1001 directly with Segurança Social before that worker’s start date.


TL;DR:

  • Automatic employer registration with Segurança Social occurs for companies formed through Empresa Online with pre-approved articles, typically within a few days and is free.
  • Sole traders must manually file the RV1001 form before hiring their first worker, as they do not benefit from automatic registration, which delays employer number issuance.
  • Most registration failures stem from missing Portuguese NIFs for foreign shareholders or unapproved acceptance-of-office declarations, which require prompt verification within 48 hours.
  • Short-term or shift contracts often require worker notification within 24 hours, making timely submissions of RV1009 crucial to avoid penalties.
  • Outsourcing Portugal offers Employer of Record services that handle registration, payroll, and compliance for companies without establishing a Portuguese entity, reducing administrative hurdles.

Outsourcing-portugal
Hire in Portugal Without a Local Entity
Outsourcing Portugal supports hiring, onboarding, payroll, legal compliance, HR, and employee settlement for international companies.

Explore outsourcing in Portugal

Table of Contents

How Does Registo De Empregador Portugal Work Step by Step?

The path you take depends on how your company gets incorporated, so pick that route first.

  1. Choose your incorporation method. Empresa Online 2.0 lets you file everything remotely; Company on the Spot (Empresa na Hora) gets you a same-day certificate at a registry desk with pre-approved articles of association. Custom articles take longer either way.
  2. Authenticate with a recognized digital ID. Portuguese authentication runs on the Citizen Card, Chave Móvel Digital, or eIDAS for other EU nationals. Foreign representatives without one of these need a Portuguese NIF and, often, a local representative to sign on their behalf.
  3. Complete the incorporation details. This means selecting your CAE activity code, listing shareholders and managers, and signing the articles of association. Get these details wrong and you’ll be correcting paperwork instead of hiring.
  4. Let the registry do the handoff. Once incorporation clears, Empresa Online transmits the data electronically to Segurança Social, which is what triggers automatic employer registration for legal entities.
  5. Confirm the registration actually landed. Check your email for the incorporation confirmation, your access codes, and evidence of NISS issuance. Don’t assume it worked. Log into the Segurança Social portal and verify.
  6. File RV1001 manually if you’re a sole trader, or if automatic registration didn’t happen. This form goes to Segurança Social directly, either online through the Direct Social Security portal or in person at a local office.

That last step catches more people than it should. Companies formed through non standard routes, or with incomplete representative data, sometimes fall through the automatic process entirely.

What Documents and IDs Do You Need Before You Start?

Gather these before you touch any online form, because a missing NIF is the single most common reason registration stalls:

  • Citizen Card or passport for every manager and shareholder, with a certified translation if the document isn’t in Portuguese.
  • A Portuguese NIF (tax number) for each individual and corporate entity involved, including foreign shareholders.
  • The company’s NIPC, the identifier the Commercial Registry uses to notify Segurança Social and issue the employer’s NISS.
  • Signed acceptance-of-office declarations from managers and administrators.
  • Beneficial-owner data for your RCBE filing, including full name, date of birth, nationality, and NIF where applicable.

The NISS is the number that actually makes you an employer of record in the system. Companies incorporated through the registry usually get one issued automatically and tied to the NIPC. Sole traders don’t get that automatic step. You have to activate employer status yourself before Segurança Social will issue an employer NISS in your name.

Pro Tip: Request NIFs for foreign shareholders and managers weeks before incorporation, not the day of. This single delay causes more failed automatic registrations than any other document issue.

How Long Does Registration Take and What Does It Cost?

Timing depends entirely on which incorporation route you pick.

  • Company on the Spot: same-day certificate, walk out with your NIPC and articles signed.
  • Empresa Online with pre-approved articles: typically within a few days for approval.
  • Empresa Online with custom articles: generally up to a couple of weeks, sometimes longer if the Registry requests corrections.

On fees, Social Security employer registration itself is free when it happens automatically at incorporation, according to gov.pt’s employer registration service. The incorporation itself is where the money goes: a pre-approved online memorandum runs around €220, while custom articles push the cost to roughly €360 or higher. On-the-spot services publish their own desk pricing separately. Corrections or expedited processing add extra fees on top. Watch for the confirmation email with your access codes and permanent commercial certificate. That’s your proof the process actually closed.

Notifying New Hires: Forms, Deadlines, and Employer Duties

Registering as an employer is only the entry point. Every worker you bring on afterward triggers its own notification obligation, and the clock on some of those is unforgiving.

  1. Notify Segurança Social of the admission. Most standard contracts follow the normal reporting cycle, but certain short-term or shift-based contracts require notification within 24 hours of the worker starting. Miss that window and you’re looking at administrative friction, sometimes penalties.
  2. Use the RV1009 form for worker admissions. It captures the worker’s NISS, start date, and contract type, and it’s submitted through the Segurança Social Direta portal. Filing is free.
  3. Use RV1011 for changes to your own employer record. This covers starting, altering, or ending your registered activity as an employer, separate from individual worker notifications.
  4. Stay current on contribution payments. Employer Social Security contributions follow a monthly cycle, and rates vary by contract type and sector, so confirm your specific obligation rather than assuming a flat figure applies.
  5. If a notification gets rejected, don’t guess at the fix. Check that the worker’s NISS is valid and active first. That’s the most common cause. If the portal keeps rejecting a valid submission, escalate to your local Segurança Social office rather than resubmitting blind.

Companies managing this internally sometimes underestimate how tight the 24 hour window is for short-term staff. A compliance checklist for hiring in Portugal is worth keeping on hand if you’re onboarding several people at once.

Sole Traders, Foreign Companies, and Beneficial-Owner Filings

Not everyone fits the standard incorporation flow, and the exceptions matter.

  • Sole traders hiring their first employee must activate employer status directly with Segurança Social and file RV1001 before the worker’s start date, since there’s no automatic trigger the way there is for incorporated companies.
  • Foreign companies need a Portuguese NIF and NIPC before anything else moves. Without it, the automatic registration flow simply has nothing to attach to. A local tax representative is often required, and any foreign-language documents need certified Portuguese translations.
  • Managers and administrators each need individual registration, and their acceptance-of-office declarations must be signed before the Registry will process incorporation.
  • RCBE filings for beneficial owners are due within 30 days of incorporation. Miss it and you’re dealing with a compliance gap on top of an incomplete employer record.
  • Keep powers of attorney and representative documents ready in advance if a director won’t be physically present for signing.

What Trips Up Even Careful Employers

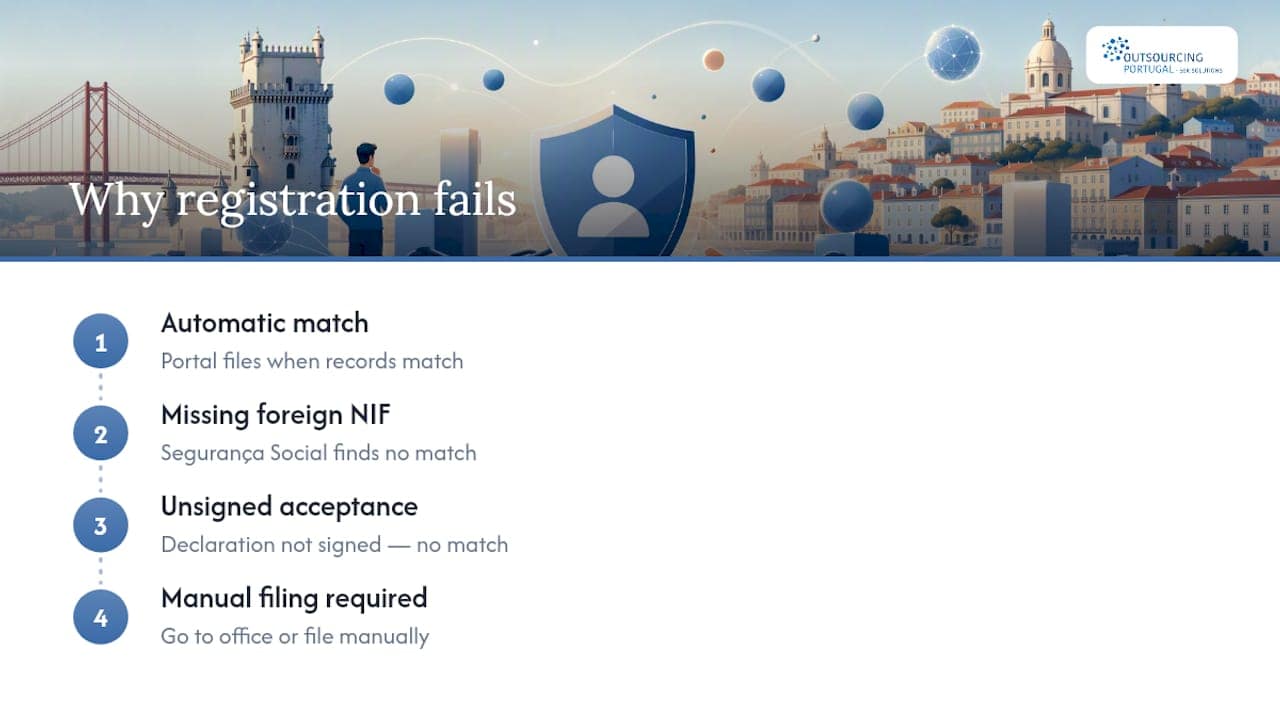
Most failed automatic registrations trace back to one of two things: a missing NIF for a foreign representative, or an acceptance-of-office declaration that never got signed. Neither looks like a big deal until Segurança Social’s system has nothing to match against, and then you’re stuck manually filing what should have been automatic.

Two causes of failed automatic registration

Run a quick check within 48 hours of incorporation. Confirm the email with your company access codes arrived, verify your NISS actually issued, and don’t let the RCBE deadline slip past 30 days. If you’re operating across multiple sites, double check the establishment code is correctly assigned. This is one of the more overlooked details, and it affects how worker admissions get routed.

Most of this is solvable through the online portals. But once you’re dealing with a foreign shareholder without a Portuguese NIF, or a registration that’s stuck for reasons the portal won’t explain, that’s when it’s worth walking into a district Social Security office instead of refreshing a webpage. Some providers handle this exact friction for foreign companies daily, and it’s rarely the paperwork itself that’s hard. It’s knowing which office solves which specific problem.

— Paulo

Let Outsourcing Portugal Handle the Registration for You

Some services remove the registration bottleneck entirely for foreign businesses that don’t have a Portuguese entity yet. Instead of chasing NIFs, signing acceptance declarations, and hoping your automatic Segurança Social registration goes through cleanly, you can work with a partner who has local tax representation and administrative relationships to get it right the first time.

Outsourcing-portugal

Through Employer of Record services, you can hire in Portugal without incorporating a company at all. Outsourcing Portugal manages worker admission notifications, payroll setup, and ongoing Segurança Social reporting on your behalf. If you’re weighing whether to incorporate directly or hire through an EOR, the EOR compliance and hiring speed guide breaks down the tradeoffs.

To get started, you’ll typically need to provide passport copies for the individuals being hired, confirmation of the role and contract terms, and your company’s existing tax registration abroad. Visit the Outsourcing Portugal hiring page to start a conversation about your specific timeline.

Sources

FAQ

How Much Does It Cost to Register a Company in Portugal?

Incorporation with pre-approved articles through Empresa Online costs around €220, while custom articles typically run about €360 or more. Social Security employer registration itself is free when it happens automatically.

How Can I Register a Company in Portugal?

You can incorporate through Empresa Online for remote filing or Company on the Spot for same-day, in-person incorporation with pre-approved articles. Both require valid IDs, Portuguese NIFs for shareholders and managers, and a chosen CAE activity code.

How Should a Company Start Activity With Social Security?

Companies incorporated through the commercial registry are automatically registered as employers with Segurança Social and issued a NISS. Sole traders must file RV1001 directly before hiring their first worker.

How Do I Register a Worker With Social Security?

Submit the RV1009 form through the Segurança Social Direta portal with the worker’s NISS, start date, and contract type. Some short-term or shift-based contracts require this within 24 hours of the start date.

What Happens If I Miss the Registration or Notification Deadline?

Late or missing employer registration and worker notifications can trigger administrative penalties and complicate payroll start dates. Businesses that need to move quickly without navigating these deadlines themselves often turn to an Employer of Record to manage compliance directly.

Visitor at Portuguese tax administration counter

Avoid Unnecessary VAT Registration in Portugal, with EOR Option

You need to register for Portuguese VAT (IVA) only when your company is legally the debtor of Portuguese IVA. The usual triggers are imports, B2C sales from Portuguese stock, intra-EU acquisitions where the seller has to register, or any deal where Portuguese law puts the tax burden on you rather than your buyer. Map your transaction flow first, then check the Portal das Finanças or talk to a fiscal representative before you file anything.


TL;DR:

  • Most foreign companies only need to register for Portuguese VAT if importing goods, selling directly to consumers from local stock, or handling ownership transfer in call-off stock arrangements.
  • B2B services typically do not require registration because reverse-charge rules let the Portuguese buyer self-account for VAT, avoiding the need for non-resident registration.
  • Registration is mandatory after customs clearance for imports, or when making B2C sales from Portuguese inventory, with the process involving formal declarations and potential appointment of a fiscal representative.
  • A fiscal representative carries joint liability for your VAT obligations and should be carefully vetted, especially if you lack a permanent establishment in Portugal.
  • Companies often mistake registration requirements, risking audits or liabilities by assuming all cross-border activities automatically trigger registration when many services or transactions do not.

Outsourcing-portugal
Hire in Portugal Without a Local Entity
Outsourcing-portugal helps international companies hire, onboard, manage payroll, and stay legally compliant in Portugal through EOR services.

Explore EOR services

Table of Contents

Who Counts as a Taxable Person for Registo IVA Empresa Estrangeira?

Under Portugal’s VAT code (CIVA), a “taxable person” is any entity carrying out an independent economic activity involving the supply of goods or services, regardless of where it’s incorporated. A non-resident taxable person is simply a foreign entity that trips this test without having a permanent establishment in Portugal. That distinction, resident versus non-resident, drives every registration decision that follows.

Most B2B services fall under reverse-charge rules. If you’re a UK software company invoicing a VAT-registered client in Lisbon, that client self-accounts for the VAT on their own return. You issue an invoice without Portuguese VAT and add a note referencing the reverse-charge mechanism. No registo iva empresa estrangeira needed in that scenario.

Imports and B2C sales work differently, because there’s no VAT-registered buyer on the other end capable of self-accounting.

  • Reverse-charge applies: consulting, software licensing, marketing services sold B2B to a Portuguese VAT number holder.
  • Registration usually required: importing goods into Portugal for resale, selling directly to Portuguese consumers, or holding local inventory.
  • Gray zone: call-off stock and consignment arrangements, where ownership timing at the point of sale decides the outcome, according to practitioner guidance from the VAT Association.

The reverse-charge exception is why so many companies register unnecessarily. If your buyer is VAT-registered and the transaction is a service, you are often off the hook entirely.

When Does Portugal Actually Require IVA Registration?

Registration obligations cluster around a handful of predictable events. Here’s the sequence most foreign companies encounter, roughly in order of how often they trip a compliance review:

  1. Importing goods into Portugal. Once you clear customs as the importer of record, you’re generally the party liable for import VAT, which usually means registering before goods move.
  2. Intra-EU acquisitions where the rules assign you the debtor role. If you’re the one bringing goods into Portugal from another EU member state and the transaction rules don’t let the buyer self-account, the obligation lands on you.
  3. B2C sales from Portuguese stock. Selling directly to Portuguese consumers, whether through a website, marketplace, or local retail arrangement, from inventory physically in Portugal, requires registration. There’s no VAT-registered counterparty to shift the liability to.
  4. Call-off stock arrangements. Ownership at the moment of sale, not at the moment of shipment, determines whether you’re on the hook. Get this wrong and you either register too early or discover an unregistered liability years later.
  5. Crossing SME exemption thresholds. The SME transfrontier exemption (the EX suffix) lets small cross-border sellers skip standard registration if they notify the Autoridade Tributária in advance and stay under the turnover conditions it sets.
  6. E-commerce volume that suits OSS instead. If you’re selling to consumers across several EU countries, the One-Stop-Shop scheme can replace multiple local registrations with a single filing, changing the registration math entirely.

Companies that get burned usually assumed one of these triggers didn’t apply to them, then found out during an audit that it did.

How Do You Register for VAT as a Foreign Company in Portugal?

Registration runs through a formal declaration, not an informal application, and the paperwork matters more than most guides suggest. Here’s the practical sequence.

  1. Confirm you actually need to register. Revisit the reverse-charge and trigger-event tests above before filing anything. Filing when you didn’t need to create ongoing compliance obligations you’ll have to unwind later.
  2. Submit the declaration of commencement of activity. Companies already registered in a business registry must file no later than 15 days after that registration, while some non-resident cases run on a longer 90-day timeline, according to gov.pt’s official VAT guidance. Non-resident legal entities without a permanent establishment file through a specific declaration procedure for non-resident legal persons.
  3. Gather your documentation. You’ll typically need company registration documents from your home jurisdiction, proof of your existing VAT or tax ID number where applicable, and a power of attorney if a representative is filing on your behalf. Portal das Finanças publishes the underlying IRIVADI form and technical instructions that list every required field.
  4. Appoint a fiscal representative if your structure requires one. Get this in writing, with the representative’s contact details ready to include on the declaration itself.
  5. File through Portal das Finanças or your local tax office. Submission channels vary slightly depending on whether you’re filing directly or through a representative.
  6. Verify the number once issued. Cross-check your new PT VAT number in VIES and confirm it’s active on the AT portal before invoicing anyone.

What to have ready before you start:

  • Certificate of incorporation or equivalent, translated if requested.
  • Existing VAT/tax identification number from your home country.
  • Signed power of attorney, if using a representative.
  • A one-page summary of your transaction flow (what you’re selling, to whom, and where goods physically sit).

Processing generally takes a few weeks once the file is complete, according to practical registration checklists from Taxenlight, though incomplete documentation is the most common cause of delay. Once you’re registered, invoicing and your first periodic return obligations start immediately, not after some grace period.

When Is a Fiscal Representative Mandatory?

Non-EU, third-country companies without a permanent establishment in Portugal generally must appoint a fiscal representative before they can register. EU-resident companies usually have the option to register directly, without one, though many choose a representative anyway for practical reasons.

The representative isn’t just a mailbox. Under Portuguese rules, they carry joint and several liability for your VAT obligations, which means choosing one carelessly creates real counterparty risk on both sides.

What appointing a representative actually involves:

  • Signing a power of attorney that spells out the scope of their authority.
  • Providing the representative’s contact and tax details for inclusion on your declaration.
  • Notifying your Portuguese buyers or partners of the representative’s role, particularly if invoices will reference their details.
  • Agreeing in writing on who handles filings, payments, and communication with the Autoridade Tributária day to day.

Pro Tip: Don’t treat the fiscal representative appointment as a formality to rush through. Because they share liability for your VAT position, vet them the way you’d vet a co-signer on a loan, not a mail-forwarding service.

What Ongoing VAT Obligations Come After Registration?

What Ongoing VAT Obligations Come After Registration? — overview diagram

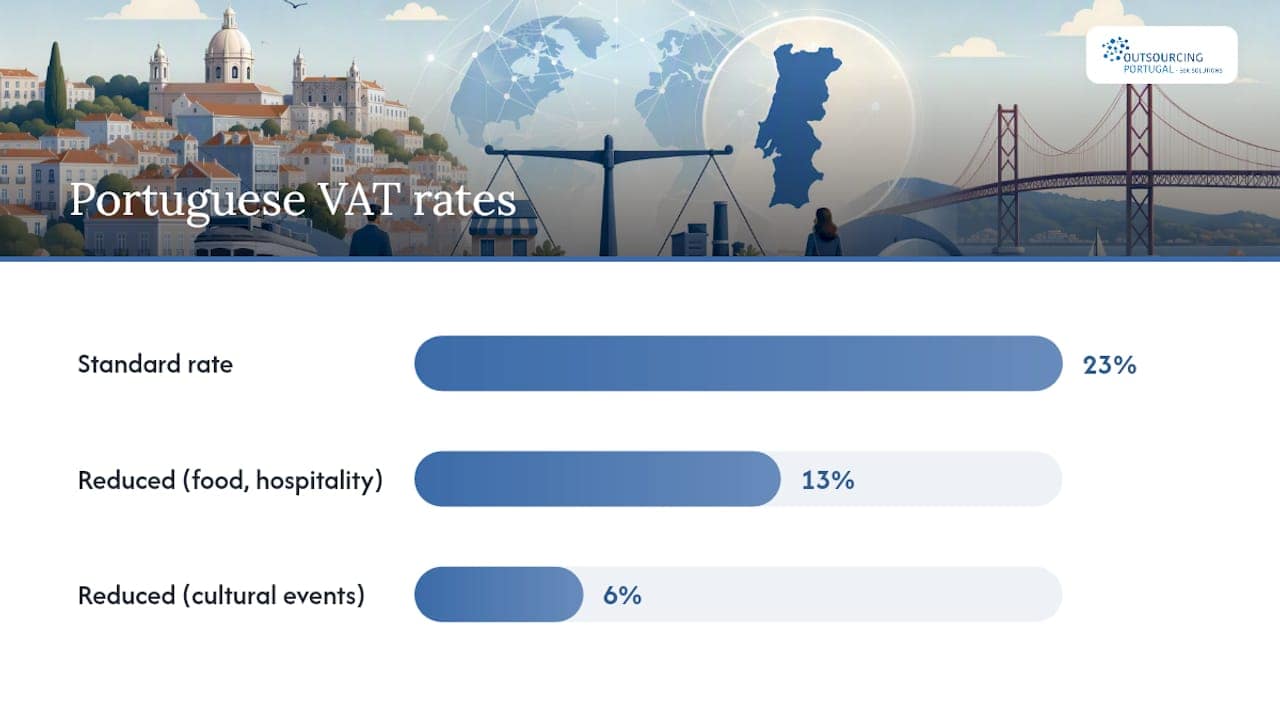
Portugal applies a standard VAT rate of 23%, with reduced rates of 13% and 6% for specific goods and services like certain food items, hospitality, and cultural events. Most B2B cross-border services stay outside these rates entirely under reverse-charge, but once you’re registered for local transactions, getting the rate right on every invoice matters.

Ongoing compliance breaks down into a few recurring tasks:

  • Invoice content. Every invoice for a Portuguese transaction needs your PT VAT number, the applicable rate or reverse-charge reference, and your fiscal representative’s details where relevant.
  • Periodic returns. Registered entities file VAT returns on a monthly or quarterly cadence depending on turnover, with payment due alongside each filing.
  • SAF-T reporting. Portugal requires standardized accounting file (SAF-T) submissions from registered businesses, which means your invoicing software needs to generate Portuguese-compliant export files, not just PDFs.
  • OSS as an alternative. If your registration need comes from EU-wide e-commerce rather than a single Portuguese trigger, the One-Stop-Shop scheme can replace this whole local filing cycle with one consolidated EU return, according to the European Commission’s national VAT rules for Portugal.

Digital services sold to non-EU customers but “used and enjoyed” in Portugal can also fall under Portuguese VAT even without a physical presence, a rule that surprises companies used to treating digital sales as location-agnostic.

What Mistakes Do Foreign Companies Make With Portuguese VAT?

The single most expensive mistake is registering when you didn’t have to. Companies see “foreign” and “Portugal” together and assume VAT registration is automatic, then spend a year filing returns for transactions that should have been reverse-charged from the start. Practitioner guidance consistently flags this as the top avoidable error.

  • Registering “just in case” instead of confirming the debtor test first.
  • Mishandling call-off stock by tracking shipment date instead of the ownership-transfer moment.
  • Skipping written confirmation of a buyer’s VAT status before assuming reverse-charge applies.
  • Letting representative communication lapse, which creates audit red flags even when the underlying tax position is correct.

Pro Tip: Before you file anything, write a one-paragraph description of exactly how goods or services move from you to your Portuguese counterparty. If you can’t clearly state who owns what and when, you’re not ready to decide on registration yet.

For companies whose only Portuguese presence is a handful of hired employees rather than product sales, an Employer of Record arrangement often sidesteps the registration question entirely, since payroll tax and employment compliance run through the EOR’s existing structure instead of yours.

EOR routes payroll and employment compliance

What I’d Tell You if You Called Me Before Registering

Most companies that call about registo iva empresa estrangeira don’t need to register at all. They need a clearer read on whether their buyer qualifies for reverse-charge. Product sellers with local stock almost always need registration; pure B2B service exporters almost never do. My first-three-step advice: confirm your debtor status against the CIVA test, decide whether a fiscal representative or an EOR route fits your actual footprint, then file only once you’re certain. Skipping straight to paperwork is how companies end up registered, liable, and still confused about why.

— Paulo

A Practical Alternative to Registering Before You’ve Even Hired Anyone

If your Portuguese footprint is really about people, not product, VAT registration might be the wrong problem to solve first. Some service providers run payroll, tax remittance, and employment compliance for companies hiring in Portugal without them setting up a local entity or VAT registration just to bring a few employees onto the books.

Outsourcing-portugal

This route tends to make the most sense for market testing, small project teams, or companies still deciding whether Portugal earns a permanent setup. Instead of appointing a fiscal representative and filing periodic VAT returns for what amounts to a payroll operation, the EOR structure absorbs those obligations directly, and you keep control of the hiring decisions. If you’re weighing registration against a faster path to hiring, check the Employer of Record Portugal services page and see whether it fits your timeline better than a standalone VAT filing would.

Sources

Start with gov.pt’s VAT guidance, the non-resident declaration procedure, the IRIVADI form instructions, and VIES to verify your number once issued. For tax filing support beyond registration, an accountant specializing in cross-border compliance can help interpret how these forms apply to your specific transaction flow.

FAQ

Are Foreign Companies Exempt From VAT in Portugal?

No blanket exemption exists. Foreign companies avoid Portuguese VAT registration only when reverse-charge applies (typically B2B services to a VAT-registered Portuguese buyer) or when they qualify for the SME transfrontier exemption after notifying the Autoridade Tributária.

How Do I Get an Intra-Community VAT Number in Portugal?

You submit a declaration of commencement of activity through Portal das Finanças or, for non-resident entities without a permanent establishment, through the specific non-resident declaration procedure; once approved, your number is valid for intra-EU transactions and verifiable in VIES.

How Do I Register Invoices Issued Abroad?

Invoices issued abroad for reverse-charge B2B transactions don’t require Portuguese VAT registration; you record them in your home-country accounting with a reverse-charge reference, while invoices tied to registered Portuguese activity must be reported through your periodic VAT return and SAF-T submission.

What Is Intra-Community VAT and How Does It Work in Cross-Border Deals?

Intra-community VAT rules determine which party in an EU cross-border transaction accounts for VAT: for B2B services, the buyer usually self-accounts under reverse-charge, while for goods, the party responsible for the acquisition (often based on who arranges transport and holds ownership at the relevant moment) typically registers and pays.

Does Hiring Employees in Portugal Trigger VAT Registration?

Hiring employees alone doesn’t create a VAT registration obligation, since employment and payroll taxes run on a separate track from VAT; companies in this position often use an Employer of Record to handle payroll compliance without touching VAT registration at all.

HR leaders reviewing Portugal tech compensation

Budget 130–145%: Portugal Tech Pay, Calculator & Incentives for HR

Budget an amount typically between one-third and nearly one-half above gross annual pay to employ a tech worker in Portugal once you add the mandatory 14-month payments, the employer social security contribution, meal allowance, and work-accident insurance. For example, a €3,000 monthly gross salary results in a total annual employer cost significantly above €40,000. Youth and long-term unemployment hiring incentives can reduce the employer social security contribution if correctly applied for before hiring.


TL;DR:

  • Employer total costs in Portugal typically range from 130% to 145% of gross salary once the 14-month pay structure, social security, insurance, and allowances are included.
  • Fixed costs like meal allowance and accident insurance weigh more heavily at entry levels, causing multipliers to be higher for junior roles than for senior positions.
  • Properly applying hiring incentives such as TSU reductions for youth or long-term unemployed hires requires early planning and accurate documentation before contract signings.
  • Using an Employer of Record is usually more cost-effective for fewer than 8 to 15 hires, while establishing a local entity becomes cheaper with larger teams.
  • Budget calculations must account for pro-rated allowances, legal contributions, and potential incentives to avoid significant underestimation of actual employment costs.

Outsourcing-portugal
Plan Your Portugal Hiring Costs
Outsourcing Portugal helps international companies manage hiring, payroll, compliance, HR support, and employee settlement without a local entity.

Explore Portugal employment solutions

Table of Contents

What Do Salários Tech Portugal Benchmarks Actually Look Like?

The multiplier changes depending on where a role sits on the pay scale, and the reason is almost entirely fixed costs. Meal allowance and accident insurance premiums don’t scale with salary the way TSU does, so they eat a bigger percentage of total cost at the entry level than they do for a senior architect earning triple the base pay.

Here’s how the multiplier typically breaks down by band:

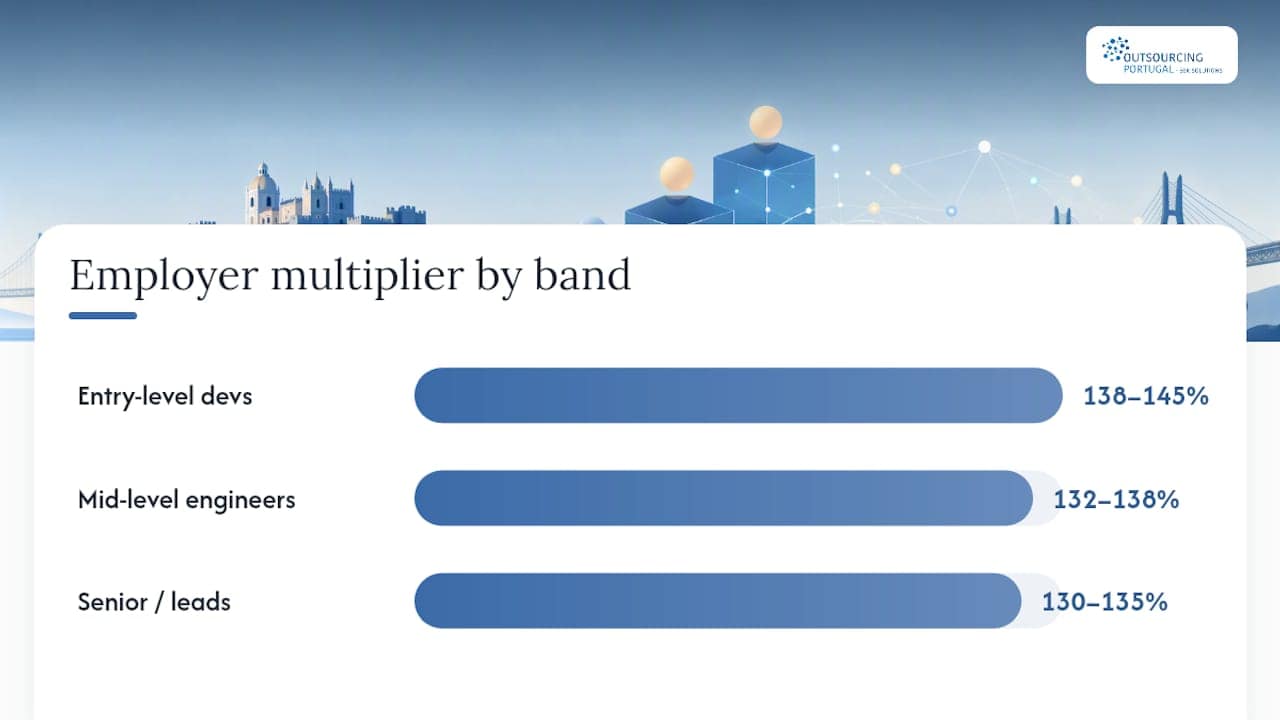
  • Entry-level developers (junior, 0 to 2 years): multiplier often runs 138% to 145%, because fixed costs like meal allowance represent a larger share of a smaller gross salary.
  • Mid-level engineers (3 to 6 years): multiplier settles closer to 132% to 138% as the same fixed costs shrink as a percentage of pay.
  • Senior and lead roles (7+ years, engineering managers): multiplier often sits at the lower end, 130% to 135%, since TSU dominates the cost structure at this point.

Employer cost benchmark: according to Simula, total employer cost in Portugal typically lands between 130% and 145% of gross pay once the 14-month structure, TSU, meal allowance, and insurance are all included.

Take a mid-level developer earning €3,000 gross per month. Multiply by 14 to get €42,000 in annual gross pay. Applying a multiplier around the typical range for this salary band yields a total annual employer cost notably above gross pay, before factoring in any hiring incentive that might reduce employer social security contributions. That gap between gross salary and real cost is the number most international hiring teams underestimate on their first Portuguese hire, and it’s precisely the kind of detail a tool that models Portugal’s tech talent market is built to clarify before you sign an offer letter.

Fed Finance’s own worked example puts the multiplier near 1.37 for a €1,500 monthly gross salary profile, reinforcing that lower salary bands carry a heavier proportional load from fixed statutory extras.

What Do Salários Tech Portugal Benchmarks Actually Look Like? — overview diagram

How to Calculate Total Employer Cost, Step by Step

Building this number correctly means separating what grows with salary from what doesn’t. Here’s the sequence that produces an accurate figure every time.

  1. Start with monthly gross salary and multiply by 14. Portugal pays 12 monthly salaries plus a holiday subsidy and a Christmas subsidy, both legally mandated. Skipping this step is the single most common budgeting error international companies make.
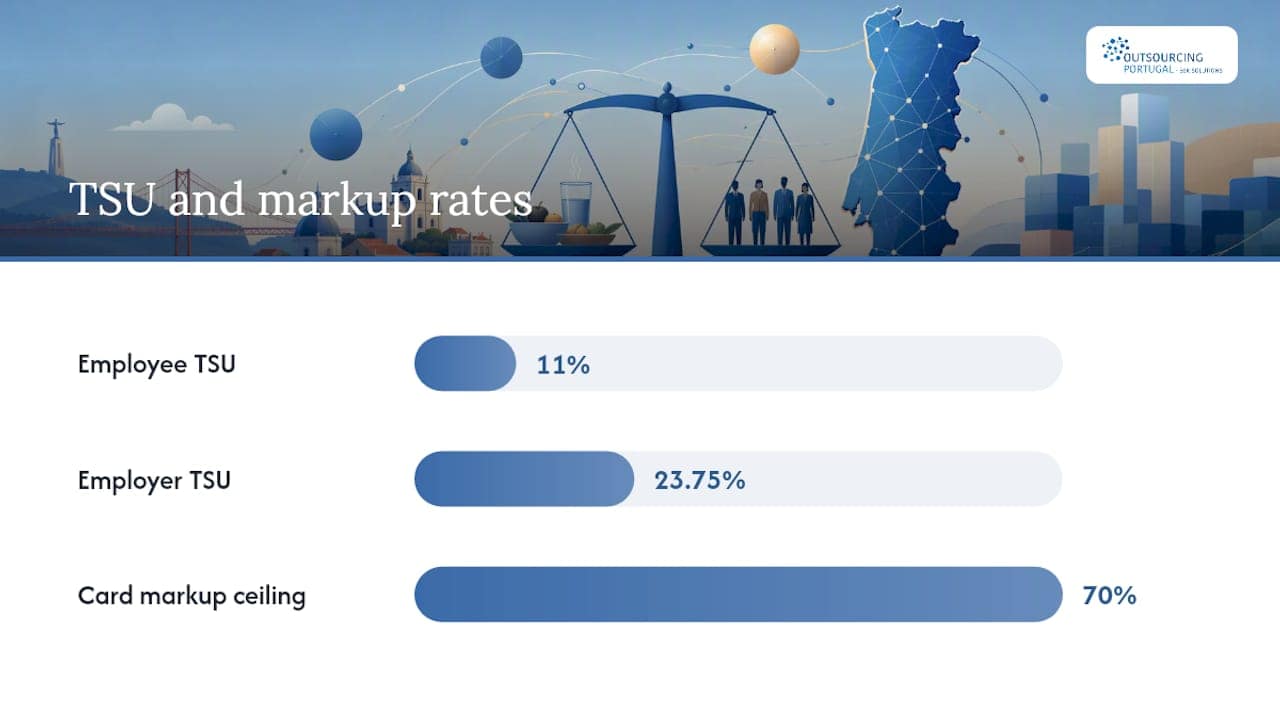
  2. Apply employer TSU at 23.75% to the full 14-month gross figure. This is the employer’s social security contribution, separate from the 11% the employee pays out of their own paycheck.
  3. Add work-accident insurance, typically budgeted around 1% of gross pay, though the exact premium depends on the insurer and role risk classification.
  4. Add meal allowance. For 2026, the tax-exempt threshold for meal allowance is higher when paid via meal card compared to cash; it should be multiplied by actual working days in the year rather than by a flat monthly figure.
  5. Apply any eligible TSU reduction or exemption for incentivized hires before finalizing the annual figure.
  6. Pro-rate for part-time contracts or mid-year starts, adjusting both the 14-month base and the meal allowance for actual days worked.

It’s a common spreadsheet error and it inflates your budget by a real amount for no reason.

Bonuses complicate this slightly. A discretionary annual bonus still incurs TSU and typically counts toward taxable income for the employee, so treat it as an additional line rather than folding it into the base 14-month calculation. A dedicated employment cost calculator built for Portugal handles these edge cases faster than a manual spreadsheet, particularly for irregular payment schedules.

Which Hiring Incentives Cut Your TSU Bill?

Portugal offers real TSU reductions for specific hiring profiles, but none of them apply automatically. You have to identify eligibility before the contract starts and file the paperwork through Segurança Social Direta.

  • First-job youth hires can qualify for a reduced TSU rate for up to five years, depending on age and prior employment history.
  • Long-term unemployed hires (typically 12+ months out of work) can trigger a three-year TSU reduction.
  • Very long-term unemployed hires may qualify for a full three-year TSU exemption in certain cases, subject to Segurança Social’s specific criteria.
  • IEFP grant programs, including Emprego +Talento and +Emprego, offer fixed grants on top of any TSU relief, with amounts indexed to the Indexante dos Apoios Sociais (IAS) and tied to contract type and minimum retention periods.

None of these are retroactive. If you sign a contract first and try to claim the reduction afterward, you’ve likely missed the window. Build the eligibility check into your offer-stage checklist, not your onboarding checklist, and keep documentation on file. Segurança Social audits these claims, and losing eligibility retroactively means repaying the difference plus penalties.

EOR or Local Entity: Which Actually Costs Less?

Speed and headcount decide this question more than anything else. An Employer of Record lets you hire in days rather than months, charging a per-employee monthly management fee on top of the statutory pass-through costs already discussed above.

Setting up a Portuguese entity means a different cost profile entirely:

  • Legal incorporation, registered office, and local accounting fees, all before your first hire even starts.
  • Ongoing fixed overhead: bookkeeping, compliance filings, and a local payroll function, regardless of headcount.
  • A break-even point against EOR fees that market analysis generally places around 8 to 15 employees, depending on your fee structure and overhead assumptions.

Below that threshold, an EOR almost always wins on total cost and certainly wins on speed. Above it, the fixed costs of an entity start to dilute across enough salaries that ownership becomes cheaper long-term.

Pro Tip: Ask any EOR provider for a line-by-line breakdown separating their management fee from statutory pass-through costs like TSU and insurance. Compare those pass-through lines against official rates. If the numbers don’t match, you’re paying a hidden markup dressed up as compliance cost.

A Compact Checklist to Budget and Reduce Cost Legally

  1. Confirm TSU incentive eligibility before making an offer, not after signing.
  2. Structure meal allowance through a meal card, not cash, to hit the higher €10.455 daily exemption.
  3. Pro-rate meal allowance to actual working days rather than a flat monthly assumption.
  4. Budget on a 14-month basis from day one, with a 1% baseline for accident insurance.
  5. Consider benefit packaging (health insurance, transport allowance) as a legally exempt way to add candidate value without inflating taxable salary.
  6. File Segurança Social declarations on time. Late filings can forfeit incentive eligibility even when the hire itself qualified.

Pro Tip: Set a recurring calendar reminder to re-check statutory rates every January. TSU percentages, minimum wage, and meal allowance thresholds all get revised, and last year’s spreadsheet formula can quietly become wrong.

What Do Developers, Engineers, and Managers Actually Earn?

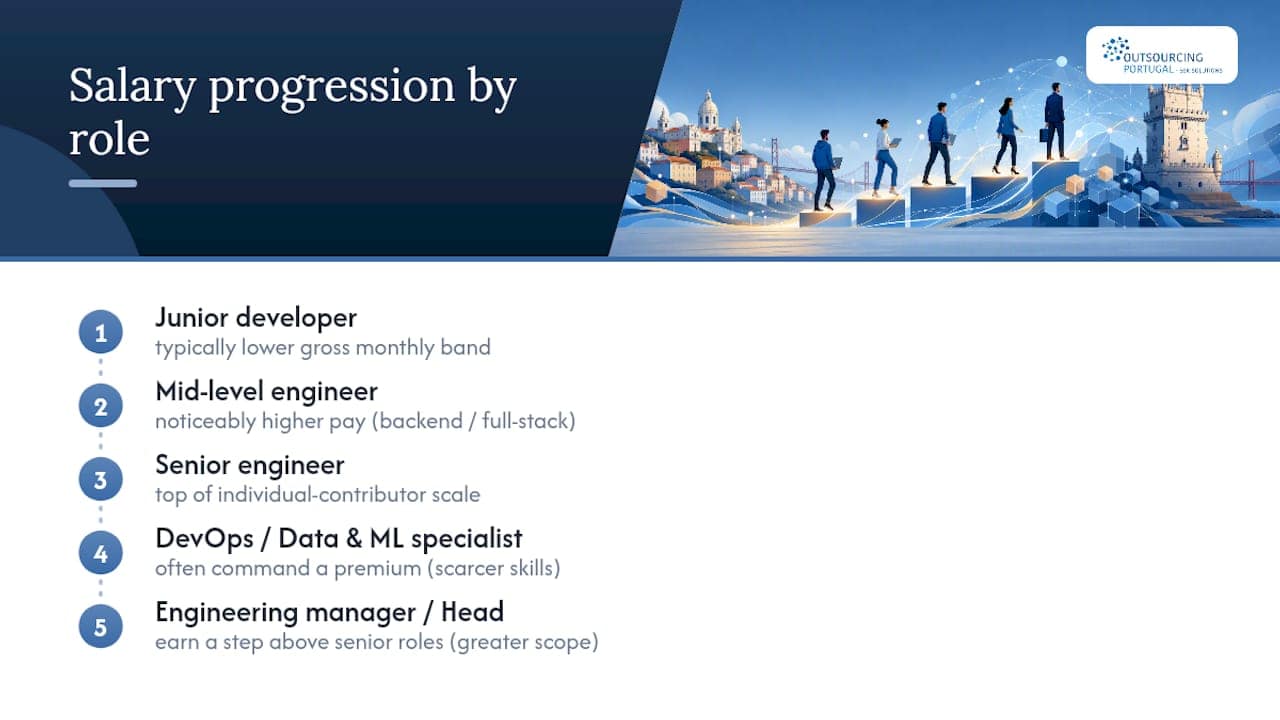
Gross salary ranges vary widely by role and seniority, and that variance is exactly what drives the multiplier differences discussed earlier. Junior developers in Portugal typically start in a lower gross monthly band, while mid-level backend and full-stack engineers command noticeably more. Senior engineers, DevOps specialists, and engineering managers sit at the top of the individual-contributor and first-line-management scale, with data and machine learning specialists often commanding a premium given the smaller talent pool.

Engineering managers and heads of engineering typically earn a further step above senior individual contributors, reflecting both scope and the smaller number of people qualified for the role. The gap between junior and senior compensation in Portuguese tech has widened over recent hiring cycles, largely because demand for senior remote-capable engineers has outpaced the local supply, while junior salaries have grown more slowly.

For international HR teams, the practical takeaway is that role definition matters more than title. A “senior developer” job posting in Lisbon can mean genuinely different compensation depending on whether the company is a local startup, a multinational with a nearshore delivery center, or a foreign-owned remote-first team. Benchmark against the specific skill set and seniority level you need, not just the job title, and build your employer-cost model around the gross figure you’d realistically need to offer to win that candidate in the current market.

Portugal tech salary progression by role

Do Salaries Vary by Region Within Portugal?

Lisbon commands the highest gross salaries for tech roles in Portugal, followed by Porto, with a noticeable gap once you move outside these two metro areas. Companies hiring in smaller cities or inland regions can often find comparable technical talent at somewhat lower gross salary expectations, though the difference has been narrowing as remote work normalizes pay expectations nationally.

This matters directly for your employer cost model because TSU, meal allowance rules, and insurance premiums don’t change by region. What changes is the gross base you’re calculating from. A Porto-based senior engineer earning a lower gross salary than a Lisbon-based equivalent will generate a correspondingly lower total employer cost, even though the percentage multiplier stays roughly the same.

Remote-first hiring has complicated this regional logic. Companies building nearshore teams increasingly recruit across the country rather than anchoring to Lisbon specifically, which means HR teams benchmarking “Portugal tech salaries” need to specify whether they mean a Lisbon-anchored figure or a national blended average. The two numbers can differ meaningfully, and using the wrong one in a budget model either overpays for talent outside the capital or underbids candidates you’re trying to recruit in it.

Where Is the Portuguese Tech Salary Market Headed?

Salary growth in Portuguese tech has tracked closely with the country’s growing reputation as a nearshore delivery hub for Western European and North American companies. Demand for senior engineering, cybersecurity, and data specialists has consistently outpaced local graduate output in those specific niches, putting sustained upward pressure on compensation for experienced hires.

Inflation and minimum wage adjustments also filter through the system every year. The national minimum wage for continental Portugal rose to €920 gross monthly for 2026 under Decreto-Lei n.º 139/2025, which pushes up the cost floor for junior hires and, indirectly, exerts upward pressure on salary bands just above minimum wage as employers maintain pay differentials.

Companies planning multi-year hiring in Portugal should expect gradual, not explosive, salary growth for most roles, with sharper increases concentrated in scarce specializations like cloud infrastructure, AI/ML engineering, and cybersecurity. Budget models built on a single year’s benchmark risk going stale within 18 to 24 months in these high-demand niches, less so for more commoditized front-end or QA roles where supply keeps pace with demand.

How Does Portugal Compare to Other European Tech Hubs?

Portugal remains one of the more cost-competitive tech hiring markets in Western Europe, sitting below Germany, the Netherlands, Ireland, and France on gross tech salaries for comparable roles, while still offering an EU-based, English-proficient, and technically capable workforce. That gap is exactly why nearshore delivery models built around Portugal have grown steadily among companies headquartered in higher-cost markets.

The comparison isn’t just about gross pay, though. Employer cost structures differ meaningfully across these countries too.

For HR teams comparing total cost of ownership rather than just headline salary, Portugal’s combination of below-average gross pay and a mid-range statutory burden usually produces a lower blended employer cost than Northern European alternatives, even after accounting for the 14-month structure. That’s the calculation that matters when deciding where to place a nearshore team, not the gross salary figure alone.

How Much Do Experience and Education Move the Number?

Experience level is the single strongest driver of salary variation in Portuguese tech, more so than the specific university or degree a candidate holds. A computer science degree from a Portuguese university carries real weight for entry-level hiring, but by the time a candidate reaches five or six years of experience, demonstrated project history and specific technical skills matter far more to compensation than academic credentials.

Self-taught developers and bootcamp graduates have become increasingly common in the Portuguese market, particularly in web development and QA, and salary data increasingly reflects skill and portfolio strength over formal education at the mid-career level. Advanced degrees still command a premium in specialized fields, particularly data science, machine learning research, and certain cybersecurity roles where a master’s degree or PhD signals depth that’s harder to demonstrate through a portfolio alone.

For employer cost modeling, the practical implication is straightforward: budget by experience band and specialization first, and treat education as a secondary adjustment rather than a primary variable, except in those narrow research-heavy specializations where formal credentials still carry outsized weight in hiring decisions.

What Benefits Do Portuguese Tech Companies Offer Beyond Salary?

Meal allowance is the most universal benefit in the Portuguese labor market, tech included, precisely because of the tax exemption structure discussed earlier. Nearly every formal tech employment contract in Portugal includes it, typically delivered via meal card rather than cash to maximize the exemption threshold.

Health insurance is the next most common addition, offered by the large majority of established tech employers and increasingly expected by candidates as a baseline rather than a differentiator. Beyond that, benefit packages in Portuguese tech companies commonly include some combination of remote or hybrid work flexibility, transport allowances, professional development budgets, and equipment stipends for home office setups.

Equity or stock options appear more often at startups and scale-ups than at larger established companies, though they remain less standardized in Portugal than in markets like the United States. For international companies building an offer package, matching local benefit norms, particularly meal allowance and health insurance, often matters more to candidate acceptance rates than matching absolute gross salary figures, since these benefits are embedded in what Portuguese tech talent expects as standard practice.

A Perspective on Hiring Tech Talent in Portugal

Portugal’s real advantage isn’t the lowest salary in Europe. It’s the combination of educated, multilingual talent, a stable regulatory environment, and a cost structure that’s genuinely competitive once you calculate it correctly. Most hiring mistakes happen at the spreadsheet stage, not the recruiting stage. Get the employer-cost math right and Portugal delivers exactly what it promises.

— Paulo

How Outsourcing Portugal Turns These Numbers Into a Hire

Running these calculations by hand across multiple candidates, salary bands, and incentive scenarios eats real time, and one missed TSU exemption or miscounted meal allowance day can throw an entire budget off. Outsourcing Portugal builds the line-by-line employer cost estimate for you, factoring in the current TSU rate, meal allowance rules, applicable hiring incentives, and your specific role and salary band, so you get one accurate number instead of a spreadsheet full of assumptions.

Outsourcing-portugal

Beyond the cost estimate, the service covers what happens after you decide to hire: Employer of Record contracts, payroll processing, onboarding, ongoing compliance with Segurança Social filings, and nearshore team setup for companies scaling beyond a single hire. You skip the entity setup, the local accounting overhead, and the guesswork on which incentives your hire actually qualifies for. If you’re ready to see what a specific role and salary band actually costs to employ in Portugal, request a tailored cost estimate and get numbers built around your exact hiring plan rather than a generic benchmark.

Sources

Check Segurança Social Direta for TSU rules, the IEFP hiring supports page for grant programs, and simula.pt’s cost simulator for a quick benchmark. Diário da República publishes the legal text behind each rate. Re-verify every January, since figures change annually.

FAQ

Can I Reduce My TSU Bill Legally?

Yes. Portugal offers TSU reductions or exemptions for first-job youth hires and long-term unemployed candidates, but you must apply through Segurança Social Direta before or at the point of hire.

Is an EOR Cheaper Than Setting Up a Portuguese Entity?

For most companies hiring fewer than roughly 8 to 15 employees, an Employer of Record like Outsourcing Portugal typically costs less than establishing and maintaining a local entity, largely due to avoided fixed overhead.

How Much Does Meal Allowance Add to Employer Cost?

For 2026, the tax-exempt meal allowance threshold is higher via meal card than cash, representing a fixed cost that HR teams should budget based on actual working days rather than a flat monthly figure.

Portuguese commercial registry building entrance

Avoid 4 Common Registration Failures for Foreign Companies in Portugal

Yes, a foreign company can lawfully operate in Portugal by creating a branch (sucursal), forming a Portuguese subsidiary, registering a one-off activity through the FCPC, or working through an Employer of Record. The right route hinges on how permanent your presence needs to be, how much liability you’re willing to carry directly, and whether you already hold Portuguese tax numbers. If you don’t have a NIF or NIPC yet, or you want people working legally in Portugal within days rather than weeks, an EoR or fiscal representative is usually the fastest lawful bridge.


TL;DR:

  • Foreign companies must obtain a NIF or NIPC before registration, with non-EU entities typically needing a fiscal representative first.
  • Registering a sucursal involves no separate legal entity and carries parent liability, while a subsidiary provides legal independence with additional paperwork.
  • Using an Employer of Record allows immediate employment of staff in Portugal without establishing a local entity, easing hiring delays.
  • Proper documentation includes recent foreign registry certificates, official translations, and compliance with registry expiry timelines to avoid delays.
  • Online registration through Empresa Online is usually cheaper and faster, but in-person processes like Empresa na Hora offer same-day setup for urgent needs.

Outsourcing-portugal
Hire in Portugal Without a Local Entity
Outsourcing-portugal helps international companies hire, onboard, manage payroll, and stay legally compliant through Employer of Record services.

Explore employment outsourcing

Table of Contents

A sucursal is the simplest permanent option. It’s a branch, not a new company. It has no separate legal personality from the parent, which means the foreign company itself carries the liability for whatever the branch does in Portugal. The Registo guidance on creating a sucursal confirms this structure and lays out the documents and timing involved.

A subsidiary, usually a Lda (private limited) or SA (public limited), is a distinct Portuguese legal entity with its own capital, its own board, and its own reporting duties separate from the parent. It shields the foreign parent’s other assets but comes with fuller incorporation paperwork.

For short-term work, a one-off registration through the FCPC (Ficheiro Central de Pessoas Coletivas) lets you get identified in Portugal without setting up a full company, ideal for isolated acts or activity under a year, as described on the Gov.

  • Sucursal: permanent presence, no separate legal identity, parent bears liability.
  • Subsidiary: separate legal entity, own capital and filings, limits parent liability.
  • FCPC one-off registration: short-term or isolated activity, minimal setup.
  • Representation contract or EoR: fastest route when you need people working in Portugal before any entity exists.

Who Can Actually Register a Branch or Company in Portugal?

Most commercial companies, cooperatives, and European Economic Interest Groupings can create a sucursal or found a Portuguese company, provided they can prove their own legal existence back home.

  • Companies from the EU or EEA generally face fewer prerequisites and don’t always need a fiscal representative.
  • Non-EU/EEA entities typically must appoint a fiscal representative before Finanças will issue a NIF, since Avalara’s guidance on fiscal representation in Portugal explains that this person or firm receives tax notifications on the foreign entity’s behalf.
  • Minors cannot act as shareholders, and companies mid-merger or mid-split face extra scrutiny.
  • Missing a Portuguese NIF or NIPC blocks the process outright, regardless of how complete everything else is.

Confirm eligibility and figure out who needs a fiscal representative before you touch the document checklist. It saves a second trip.

What Documents Do You Need, and How Should They Be Translated?

Portuguese registrars are strict about paperwork age and language. The Registo’s own guidance for creating a company states plainly that foreign partners need Portuguese NIPC and NIF, recent commercial registry certificates, and a translation for anything not already in Portuguese.

  1. A recent certidão do registo comercial (commercial registry certificate) from the parent’s home country.
  2. Updated statutes or pacto social showing current shareholders and governance.
  3. The deliberação social, the parent company’s resolution approving the branch or investment.
  4. A power of attorney naming whoever will act locally on the company’s behalf.
  5. A beneficial owner declaration and identification for all managers and shareholders.

Every document not already in Portuguese needs an official translation, and depending on the issuing country, you may also need an apostille or consular legalization before Portuguese authorities will accept it. A Chave Móvel Digital can simplify signing later steps, though some powers of attorney still require notarization.

Pro Tip: Order your translations and registry certificates in the same week you request them. Registries expire faster than people expect, and a certificate that was “recent” a month ago can get your filing bounced back.

Translation and certificate timing workflow

Why Do NIF and NIPC Come Before Everything Else?

Individuals need a NIF (tax identification number); companies need a NIPC (corporate tax number). Both the parent company and each manager or shareholder acting on its behalf typically need one before the Registo system will accept an online filing.

Practitioners who work through these filings regularly report that a missing NIF or NIPC is the single most common reason an online registration stalls or gets rejected outright, well ahead of anything to do with the business plan itself.

  • The parent company needs a Portuguese NIPC to be recognized as a legal entity in Portuguese systems.
  • Individual managers and shareholders each need a personal NIF.
  • Non-EU/EEA entities generally must appoint a fiscal representative before Finanças will issue that NIF, per Avalara’s explanation of the role.
  • You apply for NIF/NIPC at Finanças or through an accredited representative, submitting identification and proof of the entity’s existence.

Sort tax numbers out before you schedule anything else. The Madeira Corporate Services guide for non-residents makes the same point: NIFs first, everything else follows faster.

How Do You Actually File: Online, Empresa na Hora, or in Person?

The path you choose depends on how standard your paperwork is and whether you’re comfortable navigating a Portuguese-language portal alone.

  1. Check name availability first. If you want a custom company name rather than one from the pre-approved list, request a certificate of admissibility.
  2. Gather and translate documents, then submit through the Registo online portal or Empresa Online, uploading files and signing with a Chave Móvel Digital where the system allows it.
  3. Use Empresa na Hora (or Sucursal na Hora for branches) when you want same-day processing at a physical counter. Bring identification, the deliberação social, and your NIFs. Government guidance on the Balcão do Empreendedor sucursal page confirms these express regimes exist specifically for fast setup.
  4. Receive your NIPC and certidão permanente once approved. Both become the reference numbers for every subsequent registration, from Segurança Social to banking.

Going the Registo route directly avoids unnecessary intermediary steps once your documents and tax numbers are actually in order.

How Long Does Registration Take, and What Does It Cost?

Online filings through Empresa Online tend to run cheaper than in-person Conservatória visits, though exact fees depend on company type and whether you’re using the express Empresa na Hora counter service. NIF and NIPC issuance is usually the rate-limiting step: once Finanças has your paperwork and a fiscal representative is in place where required, the numbers typically come through within days rather than weeks.

  • Online constitution: generally the lower-cost route when documents are ready.
  • In-person Empresa na Hora: faster same-day processing, at a higher counter fee.
  • Recurring costs to budget beyond registration: a certified accountant (TOC), Segurança Social contributions, ongoing tax filings, and any sector-specific licenses.
  • Biggest delay risk: waiting to request NIF/NIPC and translations until after everything else is ready, instead of starting them first.

Front-load the tax number applications and translation work. Everything downstream depends on them.

What Happens After Registration? Finanças, Segurança Social, and RCBE

Getting your NIPC is the starting line, not the finish. A handful of administrative steps turn a registered entity into an operational one.

  • Declare start of activity at Finanças and register for VAT if your activity requires it.
  • Register employees with Segurança Social and appoint a certified accountant (TOC), since Portuguese companies are legally required to have one.
  • File your beneficial owner declaration in the RCBE within the statutory deadline. Missing it carries real fines, not just a warning.
  • Open a business bank account and check whether your sector needs a municipal license or specific regulatory approval before you start trading.

Opening the account itself has its own document trail, which is worth reading through in detail before you walk into a branch.

What Actually Derails Most Foreign Registrations?

Four issues account for nearly every rejection or delay: missing NIF or NIPC, an outdated registry extract, a document nobody translated, and a non-EU entity that never appointed a fiscal representative.

  • Confirm every registry certificate is current, not just “recent enough.”
  • Confirm every foreign-language document has an official Portuguese translation attached.
  • Confirm a fiscal representative is named and accepted before you file, if your entity is outside the EU/EEA.
  • If the RNPC sends back a correction request, respond quickly. Delays here often compound rather than resolve on their own.

Pro Tip: File while your certidão de admissibilidade is still valid. These certificates expire, and refiling after expiration means starting the clock over on a step you’d already finished.

When the paperwork gets complicated or you’re short on time, that’s usually the moment to bring in a local lawyer, an accountant, or a Law Firm SEO Services | Earn Trust & Win More Cases provider that can get you operating through an EoR while the entity work continues in parallel.

When Does It Make Sense to Incorporate vs. Use an EoR?

Incorporating makes sense when you need a permanent Portuguese legal footprint, local contracts, or direct control over assets and liability. It rarely makes sense when your only goal right now is hiring a handful of people fast. An EoR sidesteps the NIF, NIPC, and fiscal representative bottlenecks entirely, since someone else already holds them. Some companies work with providers offering either path, and often both in sequence.

— Paulo

Need to Hire in Portugal Before Your Entity Exists?

An Employer of Record service can be a practical alternative to waiting on NIFs, fiscal representatives, and registry corrections before your first Portuguese hire starts working. Every step above is real and necessary if you’re building a permanent branch or subsidiary, but none of it has to block you from putting people on payroll now.

Outsourcing-portugal

Through Employer of Record services, Outsourcing-portugal becomes the legal employer of your Portuguese team while you retain full day-to-day control, no NIPC, no fiscal representative appointment, no waiting on Empresa na Hora slots. If you already have people on the ground and just need compliant pay runs, payroll outsourcing in Portugal covers salary, tax withholding, and Segurança Social filings without you touching a Portuguese accounting system. And if you’re testing the market now but plan to incorporate later, the soft-landing and entity setup service lets you run EoR today and transition to your own Lda or sucursal once volume justifies it, including visa and relocation support for staff who need to move. Reach out to scope which route fits your timeline.

Where to Check the Official Rules Yourself

Before filing anything, read the source documents directly rather than relying on secondhand summaries.

Save PDF copies of every form you submit, and check RNPC guidance whenever a rule seems ambiguous.

Sources

FAQ

How do you get a NIF in Portugal for a foreign company?

Individual managers and shareholders apply for a personal NIF at Finanças or through an accredited representative; the parent company itself needs a NIPC, and non-EU/EEA entities generally need a fiscal representative appointed first.

Can you legally work for a foreign company while living in Portugal?

Yes, but the employer needs a compliant way to pay you, either its own Portuguese entity or an Employer of Record like Outsourcing-portugal’s EoR service, which handles payroll and tax withholding without the company opening a local branch.

How do you register a company in Portugal?

You reserve a name, prepare translated registry documents and a shareholder resolution, then file through the Registo online portal or in person at Empresa na Hora once your NIF/NIPC numbers are secured.

How much does registering a company in Portugal cost?

Costs vary by entity type and channel, with online filing through Empresa Online generally cheaper than an in-person Empresa na Hora visit; current government fee schedules are listed on the official Registo and Balcão do Empreendedor pages rather than fixed in advance.

Employee using meal benefit card at cafeteria

Stop Losing €95 a Month per Employee: 2026 Portugal Meal Allowance

The subsídio de alimentação is Portugal’s meal allowance, paid on top of salary to cover a worker’s cost of eating on workdays. It is mandatory only when a contract or collective agreement requires it, and not by default under the Código do Trabalho. For 2026, the public-sector daily rate is €6.15 in cash, while the meal-card exemption ceiling runs higher, and most private employers pay it through a card rather than cash.


TL;DR:

  • The 2026 public-sector meal allowance rate is €6.15 per day, with private employers referencing the higher exemption ceiling of roughly €10.455 for tax benefits.
  • The meal allowance is only mandatory if specified in the employment contract or collective agreement, with public-sector employees having a statutory entitlement.
  • Payments made via meal cards provide a higher tax-exempt ceiling than cash, making them more cost-effective for employers intending to offer the subsidy.
  • Exceeding the daily exemption ceiling triggers taxation as regular income, requiring payroll split between exempt and taxable amounts.
  • Employers should regularly review their contracts and exemption thresholds each January to ensure compliance, and consider outsourcing payroll to manage updates efficiently.

Outsourcing-portugal
Keep Portugal Payroll Compliant
Outsourcing-portugal supports payroll management and legal compliance for international companies employing people in Portugal.

Explore employment outsourcing

Table of Contents

What Is the Subsídio de Alimentação Portugal Benefit, Legally?

The subsídio de alimentação is defined in Portuguese labor practice as an extrassalarial benefit: money paid to compensate a worker’s daily meal cost, separate from base salary. The Diário da República lexicon entry on subsídio de refeição frames it exactly this way, distinguishing it from remuneration proper.

That distinction has real consequences. Because the allowance sits outside remuneration, it is generally excluded from the calculation base for seniority-linked pay, overtime, and other salary-indexed benefits, unless a contract or collective bargaining instrument (IRCT) says otherwise.

The public sector’s daily value is set annually by government portaria, not by the labor code itself. For 2026, that instrument is Portaria n.º 51-B/2026/1, published in the Diário da República, which revokes the prior year’s portaria and fixes the new rate. Private-sector employers are not bound to match this figure, but it functions as the reference point the tax code uses to calculate exemption ceilings for everyone else. Anyone verifying a specific clause should read the primary text rather than relying on a summary, since portarias are amended and republished more often than most HR calendars track.

Is the Meal Allowance Mandatory in Portugal?

No blanket law forces private employers to pay it. The obligation exists only when it appears in an individual employment contract or in the applicable collective agreement covering that sector. Many sectors have negotiated it into their IRCTs over the decades, so it is common but not legally automatic.

Civil servants are the exception. For public administration employees, the daily value fixed by Portaria n.º 51-B/2026/1 is a statutory entitlement, paid at €6.15 per day worked as of January 1, 2026.

In the private sector, once an employer commits to paying the subsidy, either explicitly or through consistent practice, withdrawing it unilaterally can trigger a breach-of-contract claim. Courts have treated a long-standing, unchallenged practice as effectively part of the employment terms, even without a written clause. Employers who want flexibility should document the benefit’s terms precisely rather than let it become an unwritten habit that hardens into an obligation.

2026 Daily Values: Cash vs. Card Limits Explained

The public-sector cash rate is €6.15 per day for 2026, set by Portaria n.º 51-B/2026/1. That figure matters beyond the public sector because it anchors the tax-exemption ceilings private employers rely on when structuring pay.

Here is the mechanism most guides skip: the IRS exemption for meal cards is not the same number as the cash exemption. Tax rules allow the card ceiling to sit 70% above the public-sector cash reference, which is why reporting on the 2026 figures puts the card exemption at roughly €10.455 per day. Pay the same benefit in cash instead of on a card, and the tax-free portion shrinks substantially, with the difference taxed as income above the lower ceiling.

That gap explains why most Portuguese employers moved to cards years ago, even before the 2026 update widened it further.

  • Cash payment: exempt up to €6.15/day for reference purposes; anything paid above the applicable cash ceiling counts as taxable income.
  • Meal card: exempt up to roughly €10.455/day, using the 70% markup rule.
  • Monthly impact: at 22 working days, a card paid at the exemption ceiling delivers roughly €230 tax-free monthly, versus about €135 for the equivalent cash payment at its lower ceiling.

For an employer choosing between formats, that monthly gap is the number worth putting in front of a finance director before any decision gets made.

IRS and TSU: How the Meal Subsidy Is Taxed

Both exemption ceilings work the same way from the worker’s side: any amount paid up to the applicable daily limit is exempt from IRS, meaning it does not count toward the employee’s taxable income for the year. It is also excluded from the Taxa Social Única (TSU) base, so the employer avoids social security contributions on that portion too.

Cross that limit, though, and the excess behaves like ordinary salary. It gets added to taxable income for IRS withholding purposes, and the employer must apply TSU contributions on the overage as if it were regular pay. Payroll software needs to split each payment into an exempt slice and a taxable slice whenever the daily rate exceeds the ceiling, rather than treating the whole subsidy as one lump.

  • Exempt portion: no IRS withholding, no TSU on the employee or employer side.
  • Excess above the ceiling: added to gross taxable pay, subject to IRS tables and full TSU (roughly 11% employee, 23.75% employer).
  • Card payments benefit from the higher 70% markup ceiling before any of this taxable treatment kicks in.
  • Cash payments hit the taxable zone sooner, since the ceiling is lower.

Accounting entries should record the subsidy on a separate payroll line from base salary, both because it is extrassalarial and because Portuguese tax authorities expect that split during audits.

Pro Tip: Run a quarterly check comparing your actual daily subsidy rate against the current exemption ceiling. Portarias change annually, and a rate that was fully exempt last year can slip into partially taxable territory the moment the government updates the reference value.

IRS and TSU: How the Meal Subsidy Is Taxed — overview diagram

Who Qualifies for the Meal Allowance and Under What Conditions?

Entitlement rules are more nuanced than a flat “everyone gets it” assumption, and they change based on hours worked and where the work happens.

  1. Full-time employees working a standard schedule generally receive the full daily value for everyday actually worked, assuming the benefit is contractually owed.
  2. Part-time employees are usually entitled on a pro rata basis, and the common threshold applied in practice is that a worker must complete more than five hours in a given day to trigger that day’s allowance. Shorter shifts often fall outside the entitlement window, though the exact cutoff depends on the governing contract or IRCT.
  3. Telework employees are entitled to the same subsidy as their office-based peers doing equivalent work, under the principle of equal treatment that Portuguese labor law applies to remote arrangements.
  4. Night-shift and rotating-shift workers sometimes see adjusted values under sector-specific collective agreements, particularly in industries like hospitality and manufacturing where shift patterns disrupt normal meal timing.

The common thread across all four categories: whatever the contract or IRCT specifies controls the outcome, not a one-size-fits-all national rule.

Calculating Monthly Subsidy Amounts and Handling Absences

The core formula is simple: daily value multiplied by days actually worked in the month. The complications show up around the edges, in absences and calendar quirks.

  1. Count working days for the month. A typical Portuguese month has either 21 or 22 working days, depending on how weekends and holidays fall.
  2. Multiply by the daily rate. At €6.15/day cash, 22 working days produces €135.30 for the month; at the roughly €10.455/day card ceiling, the same 22 days yields about €230.01.
  3. Subtract non-working days. Vacation days, public holidays, and unpaid absences are generally not paid unless the employment contract or IRCT explicitly extends the subsidy to those days, a point confirmed in guidance on meal-card usage rules.
  4. Reconcile card loads against actual attendance. Card providers typically load funds on a schedule set at the start of the month, so payroll teams need a correction process for late absences reported after the load date, to avoid overpaying.

Sick leave follows the same default rule as vacation: no subsidy unless the contract says so, since the days are not worked.

Cash, Card, or Company Meals: Comparing Payment Methods

Portugal offers employers three practical routes for delivering this benefit, and each comes with different administrative and fiscal trade-offs.

Cash payment is the simplest to administer, added directly to the payslip, but it carries the lower exemption ceiling and heavier tax exposure once payments exceed €6.15/day.

Meal cards dominate the private sector for good reason. The Pluxee guide to meal cards in Portugal confirms the fiscal logic: cards carry a materially higher exemption ceiling than cash, which is why so many companies migrated to them well before the 2026 rate increase widened the gap further.

Employer-provided meals, such as an on-site canteen or meal vouchers redeemable at a cafeteria, remain rare outside large industrial employers, mostly because of the operational overhead of running food service.

  • Cash requires no third-party provider but taxes more of the benefit once above the ceiling.
  • Cards need a provider relationship (like Pluxee or similar issuers) and carry merchant restrictions.
  • Cards cannot be converted to cash and can only be spent at authorized food and grocery merchants, a rule the e-konomista guide to meal cards spells out clearly.
  • Employer-run meal service shifts the administrative burden onto facilities rather than payroll.

Pro Tip: Before switching an existing cash-paid workforce to cards, check whether your current contracts specify “cash” by name. If they do, HR guidance on the topic notes that changing payment mode without renegotiation can trigger disputes, even when the switch objectively benefits the employee through a higher exemption ceiling.

Employer Obligations: Contracts, Records, and Compliance

Getting the meal allowance right starts with paperwork most employers underestimate. If the benefit is owed under an IRCT, the contract should reference that instrument rather than restate a figure that might change annually. If it is a company policy rather than a sector obligation, spell out the daily value, payment mode, and any exclusions for absences directly in the employment contract.

Changing an established payment mode, cash to card or vice versa, is legally possible but risky without proper process. HR analysis on the topic stresses that switching modes unilaterally invites disputes, so document the change, give reasonable notice, and get written acknowledgment where the contract allows it.

Recordkeeping matters most around days worked. Payroll needs accurate attendance data to avoid over-loading meal cards for absent employees or underpaying staff who worked extra days. Sector guidance on vale refeição costs and administration points to a common failure mode: manual tracking across multiple providers creates reconciliation errors that surface months later during an audit.

For foreign companies without a Portuguese HR team, this is exactly where payroll outsourcing or an Employer of Record arrangement removes the guesswork, since local specialists already track the annual portaria updates and adjust templates without being asked.

Special Cases: Garnishment, Sick Leave, and Maternity

Garnishment (penhora) is one of the most misunderstood areas of this benefit. Meal-card balances are generally treated as non-penhorable while they retain their character as a meal subsidy rather than ordinary salary, according to guidance in the e-konomista meal-card explainer. That protection is not absolute. Courts and enforcement authorities weigh garnishment requests against the debtor’s subsistence needs and total income, so a creditor pursuing wage garnishment can still reach funds if the overall financial picture justifies it. Treat the subsidy as presumptively protected, not categorically untouchable.

Sick leave follows the general absence rule: no subsidy accrues for days not worked, since Social Security, not the employer, covers income during most sick leave periods, and the meal allowance is tied to actual attendance.

Maternity and parental leave work similarly. Because the employee is not physically working those days, the default position is no subsidy accrual, unless a specific contract clause or IRCT extends the benefit through leave periods, which some more generous sector agreements do.

Contractual variations show up constantly in practice. Some companies pay a fixed monthly amount regardless of exact attendance, smoothing out the daily calculation, while others tie every euro to logged hours. Neither approach is wrong, but mixing them inconsistently across a workforce is a common source of internal pay-equity complaints, particularly once employees start comparing payslips.

Special Cases: Garnishment, Sick Leave, and Maternity — overview diagram

What Changed for Subsídio de Alimentação in 2026

The headline update for 2026 is the new public-sector daily rate. Portaria n.º 51-B/2026/1 raised the reference value to €6.15 per day effective January 1, 2026, revoking the previous portaria that had governed the prior rate.

When the government adjusts the reference rate, as coverage of the 2026 update explains, the card exemption ceiling rises in lockstep, pushing it to roughly €10.455/day this year.

For employers, this means payroll templates set up in prior years using the old ceiling are now out of date. Any company still running exemption calculations off last year’s figures risks either under-reporting taxable income (a compliance exposure) or over-restricting the tax-free portion of payments (an unnecessary cost to the business, since more of the subsidy could legally be exempt).

Government budget pages tracking the Orçamento do Estado also reference these annual portaria updates as part of the broader public-sector pay framework, though the specific meal-subsidy figure lives in the standalone portaria rather than the budget law itself. Employers should treat each January as a mandatory review point for this one line item, since the rate has moved nearly every year in recent memory.

Does the Meal Allowance Actually Improve Retention?

Employees in Portugal routinely cite the meal subsidy as one of the most tangible, immediately felt benefits in a compensation package, more so than benefits that pay out annually or require paperwork to claim. It lands every payday, it is visible on the payslip or card balance, and it directly offsets a real daily cost.

That immediacy carries weight in a labor market where salary negotiations move slowly but competition for skilled workers, especially in tech and multilingual service roles, remains intense. A generous meal-card program costs an employer far less than an equivalent salary increase, thanks to the TSU and IRS exemptions covered earlier, while still registering as a meaningful perk to the employee receiving it.

Companies hiring internationally into Portugal sometimes skip this benefit entirely, assuming it is a minor line item not worth the administrative setup. That is a mistake in a market where local candidates expect it as baseline practice. Omitting it, or paying it inconsistently compared to Portuguese-market peers, can make an otherwise competitive offer look thin to a candidate comparing multiple opportunities.

How Portugal’s Meal Subsidy Compares to the Rest of the EU

Portugal’s approach, a daily allowance paid through cash, card, or employer meals, sits within a broader European tradition of subsidizing worker meals, though the mechanics differ sharply by country. France runs a similar titre-restaurant voucher system with its own exemption ceilings and merchant restrictions. Belgium and Luxembourg both operate meal-voucher schemes with tax advantages comparable in spirit to Portugal’s card exemption, though the specific daily caps and eligibility rules are set independently under each country’s own tax code.

Few EU markets tie the two so mechanically, which means Portugal’s private-sector tax treatment shifts every time the government revises a single reference number for civil servants. For an international employer benchmarking benefits packages across several EU hiring markets, that volatility is worth flagging to finance teams who might otherwise assume the exemption ceiling is a fixed constant like it is in some neighboring systems.

The Compliance Checklist Employers Should Run Now

Getting this benefit right in 2026 comes down to four checks, and most employers skip at least one of them. Pull every employment contract and applicable IRCT and confirm exactly what they promise on the meal subsidy, because assumptions based on “what we’ve always done” are how disputes start.

Recalculate your exemption ceilings against the 2026 figures. If your payroll template still references last year’s card ceiling, you are either overtaxing employees or under-reporting to the tax authority.

Decide deliberately between cash and card rather than defaulting to whatever a previous HR manager set up. The card route wins on tax efficiency for nearly every company, but that decision should be documented, not inherited. And if your organization is hiring in Portugal without a local entity, weigh whether managing card providers, exemption math, and annual portaria updates internally is worth the risk compared to handing it to a specialist who already tracks this every January.

— Paulo

Let Outsourcing Portugal Handle Your Meal Subsidy Compliance

Outsourcing-portugal exists for exactly the gap this article just walked through: foreign companies that want their Portuguese employees paid correctly, taxed correctly, and compliant with the latest portaria, without hiring an internal HR team to track annual rate changes.

Outsourcing-portugal

Our payroll outsourcing service calculates the meal subsidy alongside base salary every cycle, applying the correct 2026 exemption ceilings automatically and coordinating directly with card providers so balances match actual attendance. For companies that don’t want a Portuguese legal entity at all, our Employer of Record service puts the entire employment relationship, meal subsidy included, under a compliant local structure while you keep day-to-day management of the employee. Support is provided in English, and onboarding typically enables a new hire to be operational within days rather than weeks. If you’re planning to hire in Portugal this year, contact Outsourcing Portugal for a free consultation on how the 2026 meal-subsidy rules apply to your specific hiring plan.

This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.

Sources

FAQ

How many hours must I work to receive the meal allowance?

Full-time employees typically qualify for each full day worked, while part-time workers generally need to complete more than five hours in a day to trigger that day’s entitlement. The exact threshold depends on your contract or the applicable collective agreement.

What is the minimum meal subsidy value in 2026?

There is no universal legal minimum for private-sector employers, since payment depends on contract terms. The public-sector reference value is €6.15 per day for 2026, and it functions as the anchor for private-sector tax exemption ceilings even where the employer is not required to match it.

How is the meal allowance calculated each month?

Multiply the applicable daily rate by the number of days actually worked that month, which is usually 21 or 22 days. Days not worked, such as vacation, public holidays, or unpaid absence, are excluded unless your contract or IRCT specifically extends the subsidy to those days, per guidance from the e-konomista meal-card explainer.

When can I lose the right to the meal allowance?

You lose entitlement for any day you don’t actually work, including vacation, most sick leave, and unpaid absences, unless your contract states otherwise. Switching employers mid-month, working fewer than the contractual daily-hour threshold on a part-time schedule, or having no contractual or collective-agreement basis for the benefit in the first place can also mean no entitlement exists at all.

Does Outsourcing Portugal handle meal-card setup for foreign employers?

Yes. Outsourcing Portugal’s payroll services include calculating and administering the meal subsidy, coordinating with card providers, and applying current exemption ceilings so foreign employers stay compliant without a local HR team.

Hands signing a Portuguese telework agreement

Portugal Telework Law: €20–€50 Allowance, Written Agreement Checklist

Telework in Portugal is regulated employment law, not an informal perk. The Code of Labour, as amended by Lei n.º 83/2021, requires a written agreement, obligates employers to cover extra costs, protects a worker’s right to digital disconnection, guarantees equal treatment with on-site staff, extends health and safety rules to the home, and gives workers a right to revert to in-person work under set notice terms. Special protections also apply to informal caregivers and parts of the public administration.


TL;DR:

  • A written telework agreement is mandatory in Portugal, detailing the workplace address, schedule, equipment ownership, and face-to-face contact cadence.
  • Teleworkers retain all workplace rights, including pay, career progression, digital disconnection, and the right to revert to in-person work with proper notice.
  • Employers must cover additional costs like electricity and internet but can choose either a fixed allowance or a usage-based formula, to be specified in the agreement.
  • Requests for telework must be submitted in writing with supporting evidence, and employers can refuse only if role-specific or operational needs justify it, with proper documentation.
  • Using external legal or outsourcing services ensures compliance with Portuguese law, especially for drafting agreements, reimbursement policies, and health surveillance procedures.

Outsourcing-portugal
Manage Portuguese Telework Compliance
Outsourcing-portugal supports international companies with compliant hiring, payroll, HR support, and employment solutions in Portugal.

Explore employment solutions

Table of Contents

What Does Portugal’s Telework Law Require in a Written Agreement?

Telework only becomes legally valid once it’s written down. Article 166.º of the Code of Labour, reinforced by Lei n.º 83/2021, says the arrangement must appear either as a clause in the original employment contract or as a standalone agreement signed before the person starts working remotely. A verbal understanding, an email chain, or a manager’s casual “yes” to a home office request carries no legal weight and leaves both sides exposed.

The DGAEP guidance on telework spells out what a compliant agreement must contain:

  • Identification of both parties (employer and employee)
  • The worker’s habitual workplace, meaning the specific address where telework happens
  • Normal daily and weekly working hours, plus the agreed schedule
  • Job description and professional category
  • Salary and any complementary payments tied to the role
  • Ownership of the equipment used (laptop, monitor, chair, internet connection)
  • Who is responsible for maintaining and repairing that equipment
  • How often, and in what form, in-person contact with colleagues or supervisors will happen

That last point trips up a lot of employers. The law expects a defined cadence for face-to-face contact, whether that’s a monthly office day or a quarterly team meeting, not an open-ended “come in whenever.”

The habitual workplace clause matters more than most people realize. Legal commentary from CMS’s expert guide to remote working in Portugal notes that the agreed location becomes the legal workplace for every purpose that matters: workplace accidents, occupational disease claims, and inspection rights. If an employee falls down the stairs during working hours at the address named in the agreement, that’s treated the same as an accident on a company floor. Without the written clause fixing that address, proving where and when an incident happened becomes a dispute rather than a formality.

Skipping the agreement doesn’t just create ambiguity. It exposes the employer to labour inspectorate action and weakens the company’s position in any later dispute over hours, costs, or accident liability. Academic commentary on the 2021 telework reform points out that the law was written precisely to end the gray zone that existed during the pandemic, when millions of people worked from home with no formal structure at all. Treating a 2026 telework arrangement as informal is like treating it as if it were still 2020.

What Rights Do Teleworkers Have Under Portuguese Law?

A teleworker in Portugal keeps every right a colleague doing the same job on-site enjoys. Pay, career progression, access to training, and eligibility for promotion cannot be reduced or delayed just because someone works from a spare bedroom instead of a desk in Lisbon. Working time limits and vacation entitlements apply identically too. The Code of Labour treats remote status as a location difference, not a reason to create a second class of employee.

Right to digital disconnection. Article 169.º-A gives workers a defined right to be left alone outside their agreed hours and during rest periods. Employers cannot call, message, or email with an expectation of response once the workday ends, except in genuine force majeure situations. Repeated violations can expose the employer to sanctions, and the rule applies with particular weight to households with children under eight, where the reform specifically aimed to protect family time.

Right of reversal. Workers who move into telework by mutual agreement, rather than because their job is inherently remote, generally retain a right to ask to return to in-person work. Where a notice period applies, a period of notice is generally observed in practice; an employer cannot penalize a worker for declining a telework proposal in the first place if the role doesn’t require it.

Collective representation. Teleworkers keep full access to union representation, works council communication, and internal training sessions. If a company runs an all-hands meeting or a mandatory compliance training, remote staff must be included on equal footing, whether that means a video link or travel to attend.

One detail employers underestimate: the disconnection right isn’t a courtesy policy, it’s a statutory obligation with sanction exposure attached, according to the DGAEP’s own guidance on the regime.

Who Pays for Electricity and Internet During Telework?

The employer does, by law, but Portugal’s rules leave the amount deliberately open. Article 168.º of the Code of Labour requires the employer to cover additional costs the employee incurs because of telework, naming electricity and telecommunications specifically. What the statute doesn’t do is fix a formula, a percentage, or a fixed euro figure, which is exactly where most disputes start.

Legal practice guidance from LVPA Advogados recommends employers pick one of two approaches and put it in writing before problems start: a fixed monthly allowance, or a usage-based formula tied to documented telework days. A separate legal note from Ribeiro Avelar points out that many companies land in the €20 to €50 monthly range as a negotiation baseline, though this is market practice rather than a statutory figure, and employers should check the applicable Portaria limits before assuming any amount is automatically exempt from tax or social security contributions.

Two telework reimbursement approaches illustrated

Pro Tip: Don’t wait for a worker to submit a utility bill and argue over percentages. Set the reimbursement method in the written agreement itself, tie it to a defined number of telework days per month, and revisit the figure annually. It removes the guesswork that causes most reimbursement complaints.

Beyond money, employers carry several other duties:

  • Maintain and repair any equipment provided under the agreement, and consult the worker before swapping it out
  • Provide adequate training when new tools or software are introduced
  • Keep monitoring proportionate and transparent, never through a permanently open audiovisual connection
  • Give at least 24 hours’ notice before any home visit tied to work supervision
  • Arrange health surveillance before telework starts and periodically afterward, particularly for roles with ergonomic or screen-time risk

The home address named in the agreement is treated as the legal workplace for accidents and occupational disease, which is why the written agreement and the health and safety obligations are inseparable in practice.

How Do You Request Telework, and Can an Employer Refuse?

Requesting telework in Portugal follows a fairly predictable sequence, whether the employee is asking for the first time or renegotiating an existing arrangement.

  1. Submit a written request stating the intended start date, proposed schedule, and, where relevant, the reason (caregiving responsibilities, parental status, or simple role compatibility).
  2. Attach supporting evidence if the request relies on a special status, such as documentation of informal caregiver status or a child’s age.
  3. Wait for the employer’s written response, which must include reasons if the request is refused, not a vague verbal “it doesn’t work for us.”
  4. Escalate through the labour inspectorate if the refusal seems unjustified or the employer ignores the request entirely.
  5. Request a CITE opinion in cases involving caregivers, parents, or other protected categories, since the tripartite council has direct authority to weigh in on these disputes.

Employers can lawfully refuse telework when the role genuinely requires physical presence or when company resources can’t support it, but a 2024 CITE parecer makes clear that in caregiver cases, the burden of proof sits with the employer, not the worker. Informal caregivers can hold a right to telework for up to four years, and an employer opposing that request has to follow the Article 57.º procedure and be ready to document, concretely, how remote work would disrupt operations. A vague claim of “operational needs” won’t hold up under CITE review.

Keep copies of every proposal, every reply, and every piece of cost documentation. Disputes over telework almost always come down to who kept a paper trail and who didn’t.

Building a Telework Agreement: What Should Go In It?

A solid checklist saves both sides from renegotiating basics six months in. At minimum, cover:

  • Identity of both parties and the effective date
  • The exact habitual workplace address
  • Agreed schedule, including daily start and end times
  • The reimbursement formula for electricity and internet
  • Equipment ownership and who handles maintenance
  • Digital disconnection rules, including any narrow exceptions
  • Monitoring and privacy terms, stated plainly
  • A fixed cadence for in-person contact, commonly at least once every two months
  • Health surveillance timing, both before telework starts and on a recurring basis
  • Notice period and procedure for reverting to in-person work

An internal telework policy should sit alongside individual agreements, covering which roles qualify for telework, GDPR handling for any monitoring tools, and the step-by-step procedure staff follow to request it. A structured HR compliance framework makes this far easier to standardize across a growing team than drafting each agreement from scratch.

Pro Tip: Write the policy once, then reuse it as a template for every new hire who telecommutes. Companies that draft agreement-by-agreement almost always end up with inconsistent terms that surface as problems during an inspection or a dispute.

What International Employers Get Wrong About Portuguese Telework

Most compliance headaches come down to three patterns: agreements that were copy-pasted from another country’s template and never adapted to Portuguese requirements, reimbursement policies that get decided ad hoc after a worker complains, and monitoring practices that feel normal in one jurisdiction but cross a line here.

The fix isn’t complicated. Standardize the agreement, fix the reimbursement method before day one, keep monitoring visible and proportionate, and schedule in-person contact instead of leaving it vague. Employers who understand local compliance requirements before scaling a Portuguese team avoid the scramble that comes from treating telework as an afterthought bolted onto a standard employment contract.

— Paulo

How Outsourcing-portugal Handles Telework Compliance for You

A practical alternative to building this compliance machinery from scratch is engaging specialists with local expertise. Drafting a legally sound telework agreement, setting a defensible reimbursement formula, and coordinating occupational health checks each takes real local expertise, and getting any one of them wrong creates liability that follows you long after the hire is made.

Outsourcing-portugal

Companies without a Portuguese legal entity, or without the internal bandwidth to track every clause the Code of Labour requires, typically lean on Employer of Record services to handle the agreement, the reimbursement policy, and the health surveillance scheduling under one contract. If you already have staff on the ground and just need the reimbursement and expense side handled cleanly, payroll outsourcing in Portugal covers that specifically, including the recurring cost tracking that telework reimbursements demand.

If you’re hiring your first Portuguese teleworker or converting an existing employee to a remote arrangement, get a compliance check before you sign anything. Consider consulting a local expert to review your draft agreement and reimbursement structure against current Portuguese law.

For exact statutory wording, consult Lei n.º 83/2021 directly through the Diário da República. The DGAEP FAQ offers plain-language guidance on agreement contents and employer duties, and the CITE parecer on caregiver telework is essential reading for any refusal dispute involving protected categories.

This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.

Sources

FAQ

Is Telework Allowed in Portugal’s Public Administration?

Yes. Public sector bodies operate under the same core telework framework as private employers, with the DGAEP publishing dedicated guidance for public administration staff covering agreements, disconnection rights, and eligibility.

Which Law Regulates Telework in Portugal?

Telework is governed by the Code of Labour, articles 165.º through 171.º, as amended by Lei n.º 83/2021, which remains the current legal basis for 2026.

Who Can Request Telework in Portugal?

Any employee can ask, but the law gives stronger protection to specific groups, including parents of young children and workers with informal caregiver status, who may hold a right to telework for up to four years under the CITE parecer on caregiver disputes.

How Many Breaks Am I Entitled to in an 8-Hour Workday?

Portuguese labour law generally requires a rest break during an 8-hour shift under the standard working-time rules in the Code of Labour, and telework status doesn’t change that entitlement since teleworkers keep the same working-time protections as on-site staff.

Does an Employer Have to Pay for My Internet and Electricity?

Yes. Article 168.º of the Code of Labour obliges employers to cover additional telework-related costs like electricity and telecommunications, though the law doesn’t set a fixed amount, which is why many companies agree on a fixed monthly allowance in writing.

Administrator submitting tax representative change online

Portal Steps to Appoint a Fiscal Rep in Portugal for Foreign Firms

If your company has a taxable relationship with Portugal and you live outside the EU or EEA, you must appoint a fiscal representative or enroll in electronic notifications within 15 days of the triggering event. Skip both, and the Tax Authority can fine you between €75 and €7,500. Check Gov or the Portal das Finanças to confirm which route applies to your situation.


TL;DR:

  • Foreign companies with a taxable relationship in Portugal must appoint a VAT-registered fiscal representative or enroll in electronic notifications within 15 days to avoid fines between €75 and €7,500, especially if engaged in activities like owning property, registering vehicles, signing employment contracts, or providing services subject to VAT.
  • A valid fiscal representative must have genuine tax residence or a registered office in Portugal; informal contacts or friends without VAT registration cannot fulfill legal requirements, particularly for VAT-related activities.
  • The appointment is made through the Portuguese tax portal by submitting a signed declaration of acceptance, and it remains valid as long as the taxable relationship persists, requiring annual checks to avoid unknowing lapses or non-compliance.
  • Enrolling in electronic notifications through NCEPF or ViaCTT offers a costless alternative for property owners, but it does not replace the need for a registered VAT-liable representative for VAT filings.
  • For companies with broader operations or cross-border complexities, consolidating fiscal representation, legal, and payroll compliance under an employer-of-record service can streamline Portugal’s tax obligations and reduce risks.

Outsourcing-portugal
Build Your Portugal Setup With Confidence
Outsourcing-portugal supports international companies with hiring, onboarding, payroll, legal compliance, HR support, and settlement assistance in Portugal.

Explore Portugal employment solutions

Table of Contents

Who Needs a Fiscal Representative in Portugal?

The duty kicks in the moment you create a taxable relationship with Portugal while living outside the country. That relationship can take several forms, and most foreign companies trip into one without realizing it.

You’ve established a taxable relationship if you:

  • Own Portuguese real estate, whether commercial or residential
  • Register a vehicle in Portugal under a company or personal name
  • Sign an employment contract with a Portuguese entity or employee
  • Start any activity subject to VAT, including invoicing Portuguese clients

Here’s where it gets specific: residents of the EU or EEA are generally exempt from mandatory representation. Residents of third countries, meaning anywhere outside the EU/EEA, don’t get that pass. Decreto-Lei n.º 44/2022 reshaped this rule by letting many non-residents avoid representation entirely through electronic notifications, but the exemption has a hard limit. If your business runs a self-employed activity subject to VAT, you still need a VAT-registered representative in Portugal, full stop. No amount of digital enrollment gets you out of that one.

Who Can Act as Your Fiscal Representative?

Portugal doesn’t let just anyone take on this role. The representative needs a genuine tax residence or registered office inside the country. A foreign national or foreign company can technically serve as your representative, but only if that person or entity is already resident or registered in Portugal, not simply willing to sign a form from abroad.

The VAT scenario adds another layer. If your business carries out self-employed activity subject to VAT, the representative must be a VAT-taxable person resident in Portugal, and in certain VAT situations, that representative can carry joint liability for tax obligations. That’s a meaningfully bigger commitment than passively receiving mail on your behalf.

In practice, three categories of people take on this role:

  • Individual residents, often a trusted local contact, workable for simple property ownership cases but risky for anything involving VAT or ongoing filings
  • Certified accountants, a solid fit for companies that need regular tax return support alongside representation
  • Lawyers and specialized tax firms, better suited to companies facing disputes, complex cross-border structures, or joint VAT liability exposure

Pro Tip: Never appoint a friend or informal contact as your fiscal representative if your company has any VAT-subject activity. If they aren’t a VAT-taxable person registered in Portugal, the appointment doesn’t satisfy the legal requirement, and you’re still exposed to the fine.

How Do You Appoint a Fiscal Representative in Portugal?

Most companies handle this online, though an in-person route exists for anyone who prefers it or hits a technical snag.

  1. Log into Portal das Finanças using your NIF (Portuguese tax number) and password.
  2. Navigate to “Todos os Serviços” and select “Dados Cadastrais,” then choose “Representante.”
  3. Select “Entregar Nomeação” and pick the correct scope, either IRS alone or the combined IVA & IRS scope if VAT is involved.
  4. Submit the representative’s details along with a signed declaration of acceptance or power of attorney confirming they agree to the role.
  5. Wait for the representative to formally accept the nomination through their own Portal das Finanças account. An appointment without express acceptance is not valid.
  6. Alternatively, visit a Serviço de Finanças office or a Loja do Cidadão in person, where staff can process the nomination and confirm acceptance on the spot.

Keep proof of the representative’s consent on file. If a dispute ever arises over whether representation was properly in place, that documentation is what protects you from a fine you didn’t actually deserve.

What Are the Electronic-Notification Alternatives?

Instead of naming a person, you can opt into electronic notifications through two channels: NCEPF on the Portal das Finanças and ViaCTT, Portugal’s digital mail service tied to the postal operator. Enrollment happens directly on the portal under your tax profile settings, and once active, official notices land in your digital mailbox instead of a paper letter sent to a representative.

This route has become popular with non-resident property owners for a simple reason: it costs nothing and delivers notices faster than relying on a third party to forward them. No representative fees, no coordination lag.

But the limitation matters. Electronic notifications do not substitute for representation when you’re conducting a VAT-subject self-employed activity. If that describes your situation, you need the VAT-registered representative regardless of whether you’ve also enrolled in NCEPF or ViaCTT. The two systems solve different problems, and conflating them is one of the more common mistakes foreign business owners make.

How Do You Choose the Right Fiscal Representative?

Run through this checklist before signing anything:

  • Confirm the candidate has genuine Portuguese tax residence or a registered office, not just a mailing address
  • Verify VAT registration if your activity requires a VAT-taxable representative
  • Get written acceptance of the appointment, not a verbal agreement
  • Clarify the scope of services: is this pure representation, or does it include ongoing filings?
  • Ask about fees upfront, including any per-filing or annual retainer costs
  • Check language capability, since misunderstandings over tax correspondence create real risk
  • Ask about professional indemnity insurance, particularly for joint-liability VAT situations

Provider type should match your complexity. Certified accountants work well for companies that need routine filings alongside representation. Lawyers make more sense when you’re facing disputes or a tangled cross-border structure. Specialized tax firms, including those detailed in guidance from PH Advogados, tend to suit companies that want full-service compliance handled under one roof rather than juggling separate vendors. Accountants weighing their own client outreach might also look at SEO support built for accounting practices as a way to grow that side of their business.

Pro Tip: Insist on a written acceptance letter that spells out the representative’s exact responsibilities and fee structure before you submit the nomination. A vague verbal promise to “handle it” is the single biggest red flag in this entire process.

How Long Does a Fiscal Representative Appointment Last?

There’s no fixed expiration date stamped on the appointment itself. Representation stays valid as long as the taxable relationship that triggered it continues to exist. Own a Portuguese property for ten years, and your representative arrangement should, in theory, run the same course, provided nothing changes on either side.

That said, the appointment isn’t indestructible. It ends automatically if the underlying trigger disappears, say you sell the property, terminate the employment contract, or wind down the VAT-subject activity that required a VAT-registered representative in the first place. It also ends if you become an EU/EEA resident, since that shifts your status out of the mandatory-representation category entirely.

Representatives can resign, companies can dissolve, individuals can move away from Portugal themselves. None of those events trigger an automatic notification to you. This is why periodic check-ins matter more than most foreign companies assume. A representative who quietly stopped being eligible, because they relocated abroad or lost their VAT registration, leaves you unknowingly out of compliance until a notice goes unanswered and the fine shows up.

Build a calendar reminder to reconfirm your representative’s status at least once a year, especially if your company’s Portuguese footprint has shifted (new property, new hires, a wound-down VAT activity). Treat the appointment as a living arrangement tied to your actual tax situation, not a one-time box you checked and forgot about.

How Long Does a Fiscal Representative Appointment Last? — overview diagram

What Does a Fiscal Representative Actually Do?

The role goes beyond forwarding mail, though that’s the part most people picture. A fiscal representative acts as the official point of contact between your company and the Portuguese Tax Authority for every notice, deadline, and administrative communication tied to your taxable relationship.

Practically, that means the representative:

Receives and forwards tax notices, assessments, and deadline reminders on your behalf, ensuring you actually see communications that would otherwise go to an address you don’t check. It ensures your company meets filing deadlines tied to whatever triggered the representation, whether that’s an annual property-related return or recurring VAT filings. In VAT-subject cases, the representative may hold joint liability for certain tax obligations, meaning their exposure isn’t purely administrative; they carry real financial risk alongside you. It serves as your point of contact for any Tax Authority correspondence, including audits, information requests, or clarification demands.

Fiscal representative duties and VAT liability

That joint-liability piece deserves emphasis. A representative handling straightforward property ownership faces limited exposure. One handling active VAT filings for your business takes on genuine financial risk if returns are wrong or late, which is exactly why VAT representatives tend to charge more and screen clients more carefully before accepting the role.

Without a properly appointed representative or an active electronic-notification enrollment, you also lose the ability to exercise your rights before the Tax Authority, including filing complaints or appeals, a consequence that catches many companies off guard only after they’ve already missed something.

How Do You Revoke or Change Your Fiscal Representative?

Switching representatives follows roughly the same path as the original appointment: log back into Portal das Finanças, navigate to the same “Representante” section under “Dados Cadastrais,” and submit a new nomination naming the replacement.

The new appointment doesn’t take effect until the new representative formally accepts it through their own account, mirroring the acceptance requirement from the initial nomination. Until that acceptance registers, your prior representative technically remains on record, so don’t assume a submission alone completes the switch.

If you’re revoking representation entirely, perhaps because you sold the property or wound down the VAT activity that triggered the requirement, you’ll want to confirm with the Tax Authority that the underlying obligation has genuinely ended before assuming you’re free of the requirement. Simply removing a representative’s name without addressing the taxable relationship that created the duty can leave you non-compliant, even if no one is actively representing you anymore.

Companies switching from an informal individual representative to a professional firm should plan for a short overlap window. Have the outgoing representative confirm in writing that all pending filings and notices are up to date, then hand that documentation to the incoming representative before finalizing the changeover. Gaps in this handoff are where notices get missed and fines start accumulating, often without either party immediately realizing it.

Does EU or Non-EU Status Change Your Obligations?

Your company’s home jurisdiction determines almost everything about whether this requirement applies to you at all. Residents of the EU or EEA generally don’t face the mandatory fiscal representative rule, a distinction rooted in the mutual assistance and information-exchange frameworks that member states share with each other.

Companies based outside the EU/EEA, think the United States, United Kingdom, Brazil, or most of Asia, fall squarely into the category that requires either a Portugal-based representative or enrollment in electronic notifications. That’s the core distinction driving this entire compliance area, and it’s worth restating because so many foreign business owners assume the rule is universal when it specifically targets third-country residents.

The VAT exception cuts across both categories, though. Whether you’re an EU company or a third-country company, if you’re conducting self-employed activity subject to VAT in Portugal, you need a VAT-registered representative resident in the country. EU status doesn’t exempt you from that particular requirement; it only exempts you from the broader representation mandate tied to property ownership, vehicle registration, or employment relationships.

This is where companies often misjudge their exposure. An EU-based business assumes it’s off the hook entirely because it read about the general exemption, then gets caught operating VAT-subject activity without the representative that specific activity requires.

How Does This Affect VAT Filing and Payments?

For companies running VAT-subject activity, the fiscal representative isn’t a passive mailbox; they’re operationally embedded in your filing cycle. Portuguese VAT returns follow monthly or quarterly schedules depending on your turnover, and the representative typically handles submission of those returns alongside payment coordination.

Because the VAT representative can carry joint liability in specific cases, late or incorrect filings expose both your company and your representative financially. That shared risk tends to shape how thoroughly a VAT representative reviews your figures before submission, often more rigorously than a representative handling pure property-related notices would.

Payment timing matters just as much as filing accuracy. Portuguese VAT payments are due alongside the return itself, and a representative who’s slow to process documentation from your side can create a scramble against the deadline. Companies running active sales into Portugal should build a documentation pipeline that gets invoices and records to their representative well ahead of filing dates, not the week the return is due.

If your Portuguese operations extend beyond simple VAT compliance into full payroll and employment tax obligations, that’s a related but distinct set of requirements worth understanding on its own, covered in detail in this guide to employment tax returns for Portugal hires.

A Practitioner’s View on Getting This Right

The mistake Paulo sees most often isn’t ignorance of the rule, it’s timing. Companies find out about the 15-day window after it’s already closed, usually when a fine notice arrives instead of a routine reminder. The second most common issue: informal “representatives,” a friend, a former colleague, someone’s cousin who lives in Lisbon, who don’t hold VAT status and can’t legally satisfy the requirement once a business activity crosses into VAT territory.

A professional solution closes both gaps. It builds the 15-day clock into onboarding instead of treating it as an afterthought, and it puts someone with actual VAT standing in the role when the business needs it.

Some companies work with providers that assist international businesses in navigating compliance alongside broader employment and payroll setup in Portugal, because representation rarely exists in isolation from the rest of a company’s tax footprint here.

— Paulo

Solving Fiscal Representation Alongside Your Broader Portugal Setup

If your company is past the point of needing a single fiscal representative and is actually hiring, paying, or building a team in Portugal, representation becomes one piece of a much larger compliance puzzle. That’s where a coordinated approach pays off: instead of managing a standalone representative, payroll provider, and legal filings separately, Employer of Record services from Outsourcing-portugal fold tax registration, local filings, and payroll compliance into a single managed relationship.

This matters most for companies that started with a simple representative arrangement, maybe to own property or hire one contractor, and have since scaled into something bigger. An EOR structure removes the patchwork of separate vendors and puts one accountable party behind your entire Portuguese compliance picture, from onboarding through ongoing tax obligations.

Sources

FAQ

Who Can Be My Fiscal Representative in Portugal?

Anyone with genuine tax residence or a registered office in Portugal can serve as your representative, including individuals, certified accountants, lawyers, or specialized tax firms. If your business runs VAT-subject self-employed activity, the representative must specifically be a VAT-taxable person resident in Portugal, not just any resident willing to take the role.

How Do I Get a Power of Attorney for a Fiscal Representative in Portugal?

You’ll typically draft a signed declaration of acceptance or power of attorney naming the representative and confirming their agreement to the role, then submit it alongside your nomination on Portal das Finanças. A lawyer or notary can help formalize this document if your company wants added legal certainty around the arrangement.

What Do I Need to Get a Fiscal Representative Set Up?

You need the representative’s identifying details, a signed acceptance declaration or power of attorney, and access to Portal das Finanças to submit the nomination under “Dados Cadastrais.” The appointment must be completed within 15 days of the triggering event, or you risk an administrative fine ranging from €75 to €7,500.

How Do I Avoid Double Taxation Between Brazil and Portugal?

Double taxation between Brazil and Portugal is governed by their bilateral tax treaty, which allocates taxing rights and offers credit mechanisms depending on income type and residency status. Because treaty application depends heavily on your specific facts, income source, and residency history, consult a qualified cross-border tax professional rather than relying on general guidance for this particular question.

What Happens if I Don’t Appoint a Representative or Enroll in Electronic Notifications?

You risk an administrative fine between €75 and €7,500, and you lose the ability to exercise certain rights before the Tax Authority, including filing complaints or appeals. Notices are still considered validly served even if you never see them, which can compound the problem well beyond the initial fine.

Specialist reviewing flexible benefits allocations

2026 Portugal Update: Flexible Benefits Without Hiring Payroll Staff

Flexible employee benefits are legal in Portugal, and when structured to respect Autoridade Tributária and Segurança Social rules, they raise employees’ take-home value without raising gross payroll cost. The strongest early wins are the meal card, vales infância, and health insurance, each carrying specific exemption limits. Getting the fiscal treatment wrong turns a benefit into taxable income retroactively, so payroll alignment isn’t optional.


TL;DR:

  • Payroll reconciliation and strict adherence to exemption conditions are essential to prevent benefits from becoming taxable retroactively.
  • Starting with a small, focused set of categories like meal, childcare, and training minimizes compliance risks and simplifies payroll controls.
  • Using a platform with automatic fiscal limit enforcement and comprehensive reporting reduces the chance of unintentional tax liabilities.
  • Outsourcing benefits administration and payroll functions ensures ongoing compliance and eases the operational burden for companies without dedicated payroll teams.
  • Structuring benefits as a flexible, employee-selected budget increases take-up without increasing overall payroll costs, provided the legal and tax rules are followed precisely.

Outsourcing-portugal
Simplify Portugal Payroll Compliance
Outsourcing-portugal supports hiring, payroll management, legal compliance, and HR support for companies employing people in Portugal.

Explore employment solutions

Table of Contents

What Are Flexible Benefits and How Does the Model Work in Portugal?

A flexible benefits plan gives each employee a fixed budget, then lets them allocate it across approved categories instead of receiving one fixed perk everyone gets whether they want it or not. A single parent might route most of their budget toward vales infância while a recent graduate puts it toward training or a tech stipend. Both employees cost the company the same amount; they just spend it differently.

Operationally, the budget usually lives on a card or in an app tied to a benefits platform. Each month, the employer loads the allocated amount, the employee spends it within eligible merchant categories, and the platform reconciles spending against the tax-exempt limits automatically. Unused balances typically roll over for a defined period, though rules vary by provider and by category, since a meal allowance and a wellness budget don’t behave the same way under Portuguese tax law.

Before rollout, most companies define:

  • A monthly or annual budget per employee, often segmented by role or seniority
  • Which categories are included (meal, childcare, health, transport, training)
  • Eligibility rules (probation period, full-time vs. part-time, contract type)
  • A pilot group to test the platform and communication before a full rollout

Which Benefits Are Most Common in Portugal and How Are They Taxed?

Close to half of Portuguese companies now offer some form of flexible benefits, with childcare support, education, professional training, technology stipends, health insurance, and pension plans topping the list. The mix matters because each category carries its own exemption rules, and mixing them incorrectly on a payslip is the fastest way to create an unplanned tax liability.

The meal allowance is the benefit most employees notice first. Paid in cash, it carries a lower exemption threshold than when paid onto a card, where the commonly cited exemption reference sits around €10.46 per day. A worked comparison from Pluxee’s guide shows that structuring the same allowance through a card rather than cash can measurably increase what lands in an employee’s pocket, without costing the employer more.

Here’s how the main categories typically stack up:

Benefit Typical structure Fiscal note
Meal allowance Card or cash Card payments carry a higher exemption threshold than cash under current guidance
Vales infância (childcare) Voucher or reimbursement Specific tax advantages apply under CIRC when conditions are met
Health insurance Employer-paid premium, sometimes family coverage Can be exempt if it meets CIRC conditions and treats eligible employees equally
PPR (retirement savings) Employer or employee contribution Subject to its own contribution ceilings and holding-period rules
Transport / mobility Card, subsidy, or public transport pass Generally treated favorably when tied to commuting
Technology stipend Card or reimbursement Usually treated as taxable unless structured under a specific exemption

Vales infância deserve special attention because the tax advantage under CIRC is one of the more generous exemptions available, which is why it consistently ranks among the most-used benefits in the Aon survey data. Health insurance and PPR both require closer documentation. Miss the equal-treatment condition or skip the paperwork, and the exemption disappears even if the benefit itself was legitimate.

How Do You Design a Flexible Benefits Plan Step by Step?

Building a plan that survives an audit and actually gets used takes more than picking a vendor and turning it on. Follow this sequence:

  1. Audit your workforce. Run a short survey or a few focus groups to find out what employees actually want. A workforce heavy on parents will value vales infância differently than a workforce of recent graduates chasing training budgets.
  2. Set a sustainable per-employee budget. Decide the number before you decide the categories, and set eligibility rules (tenure, contract type, full time vs. part time) up front so nobody discovers an exclusion after launch.
  3. Prioritize tax-efficient categories. Meal cards, vales infância, and health insurance tend to deliver the most value per euro spent because of their exemption treatment.
  4. Set vendor requirements. The platform must integrate with payroll, enforce fiscal limits automatically, and produce audit-ready reports. Don’t take a vendor’s word for compliance without seeing the reporting output.
  5. Communicate before you launch. Employees need to understand why a card payment beats cash for the same meal allowance. Unclear communication is one of the more common reasons adoption stays low even after a plan is funded.
  6. Pilot, then scale. Launch with one department or a small group, track adoption and satisfaction, then expand based on what actually gets used rather than what looked good on paper.

The most common mistake is offering too many categories at once, which fragments small budgets and overwhelms payroll controls. A second common mistake is letting managers approve exceptions informally, which breaks the equal-treatment condition several exemptions depend on.

Pro Tip: Start with three categories, not eight. A tightly scoped pilot with clean payroll data is easier to defend in an audit than a sprawling menu nobody fully understands.

What Vendor Types and Platforms Operate in Portugal?

The Portuguese market has matured into three broad vendor categories, and each solves a slightly different problem.

Meal-card issuers handle the highest-volume, most standardized benefit: the daily meal allowance loaded onto a card with a defined merchant network. Multi-benefit platforms go further, letting employees split a single budget across meal, childcare, health, and training from one app. Insurers and brokers offer a third route, usually for companies that want a more consultative setup alongside health coverage.

A few names illustrate how these categories differ in practice:

  • Cobee by Pluxee combines a multi-category card and app with automated fiscal-limit enforcement, and its implementation guide walks through how expenses map to categories in real time.
  • Edenred Flexível operates a broad acceptance network across meal, education, health, and senior-care spending, positioning itself as a national multi-benefit option.
  • Howden Compensa takes a broker-led approach, pairing a technology platform with consultative service for companies that want bespoke plan design rather than a self-service menu.
  • Coverflex is frequently cited in Portuguese fiscal guides as a flexible-benefits card provider covering multiple categories under one account.

Whichever route you choose, the essentials don’t change: payroll integration, automatic enforcement of fiscal ceilings, a merchant network employees actually use, and reporting detailed enough to survive a tax review. Behind the scenes, most platforms recharge balances monthly and reconcile spending against exemption limits before the payslip is finalized, which is the step that prevents a benefit from silently becoming taxable income.

What Compliance Checks Protect Your Flexible Benefits Exemptions?

The exemption on any flexible benefit depends on meeting specific conditions, not just labeling a payment “benefit” on a payslip. Miss a condition, and the Autoridade Tributária can reclassify the payment as ordinary salary, applying IRS and TSU retroactively.

What Compliance Checks Protect Your Flexible Benefits Exemptions? — overview diagram

Legal and tax commentary is direct on this point: a benefit that creates an economic advantage is taxable unless an explicit exemption applies, which puts the burden on the employer to document why a given payment qualifies. The most common way employers lose an exemption isn’t fraud. It’s inconsistency: paying the meal allowance in cash for some employees and by card for others, or letting one manager approve a benefit informally that HR never documented for the rest of the team.

Before you rely on any exemption, check:

  • Whether the benefit applies equally to all eligible employees, since differential treatment for tax-exempt benefits risks triggering taxation across the whole group, not just the affected employee.
  • Whether the payment method matches the exemption rule (card vs. cash for meal allowances carry different thresholds).
  • Whether documentation exists showing the benefit’s business rationale and eligibility criteria.
  • Whether your platform’s reporting can produce an audit trail on request.

With close to half of Portuguese employers already running some form of flexible benefits program, tax authorities have more precedent to draw on when reviewing plans, which raises the cost of a sloppy setup. When a benefit’s tax treatment is unclear, get counsel before rollout rather than after an audit flags it.

How Does Outsourcing Reduce Compliance Risk for Benefits Administration?

Running flexible benefits well means somebody has to reconcile card spending against exemption limits every single month, cross-check eligibility rules, and keep payroll filings consistent with whatever the benefits platform reports. A specialist payroll or Employer of Record partner already handles that reconciliation as part of standard payroll operations, catching mismatches between what a platform paid out and what a payslip should reflect before they become a tax exposure. That operational layer, tax filings, social security contributions, and documentation checks, is where most in-house HR teams without a dedicated payroll specialist tend to fall behind.

Flexible benefits compliance reconciliation process

Why Small Pilots Beat Big Launches

The pattern worth watching in Portugal’s flexible benefits market isn’t which platform has the most features. It’s that companies overestimate how many benefit categories employees actually want at once. Start with the meal card, vales infância, and one training or health option. Run it as a genuine pilot, watch adoption for a full payroll cycle, then expand. Document your eligibility rules in writing before you launch anything, because that’s the paperwork that protects your exemptions later.

— Paulo

How Outsourcing-Portugal Handles Payroll and Benefits Compliance

Outsourcing-Portugal is the alternative to hiring an in-house payroll team from scratch when you need benefits administered correctly from day one. Instead of researching CIRC exemption conditions or building payroll controls yourself, you get Employer of Record services that fold benefits administration into the same compliance process handling contracts, tax filings, and social security contributions for your Portuguese team.

Outsourcing-portugal

For companies that already have a legal entity in Portugal and just need payroll and benefits run correctly, payroll outsourcing covers the same reconciliation work without requiring a full EOR relationship. Either route gets you English-speaking support and a team that already knows how Portuguese exemption rules apply in practice, so a flexible benefits plan doesn’t become a liability six months after launch. If you’re weighing whether to build this in-house or hand it off, request a quote and compare the real cost of each path.

Sources

FAQ

What Types of Tax-Exempt Benefits Exist in Portugal?

The main categories include the meal allowance, vales infância (childcare vouchers), health insurance, PPR contributions, and transport support, each with its own exemption conditions. A benefit stays exempt only if it meets the specific rule for that category and is applied equally to eligible employees, as Comparaja’s fiscal guide explains.

What Is a Flexible Benefits Plan?

A flexible benefits plan gives each employee a set budget to allocate across approved categories, such as meal, health, childcare, and training, rather than one fixed perk for everyone. Close to half of Portuguese companies already run some version of this model, typically through a card or app tied to a benefits platform.

Which Merchants Accept the Coverflex Card?

Coverflex operates within Portugal’s flexible-benefits card category, generally accepted at merchants covering meal, health, education, and mobility categories, similar to other national card providers. Exact merchant networks vary by provider and update regularly, so check the current list directly on the provider’s platform before relying on it for a specific purchase.

What Are the Main Benefits of a Flexible Benefits Card Like Coverflex?

Cards in this category let employees direct a single employer-funded budget toward the categories that matter to them, from meal spending to childcare, instead of receiving one fixed perk. The main advantage over a traditional benefit is flexibility paired with automatic enforcement of fiscal exemption limits, which reduces the manual payroll work HR would otherwise need to do.

Does Outsourcing-Portugal Handle Benefits Administration Directly?

Outsourcing-Portugal integrates benefits administration into its Employer of Record and payroll services, handling the reconciliation and compliance work that keeps a flexible benefits plan aligned with Portuguese tax rules. Pricing depends on the scope of services required and is available on request.